Category Archives: Uncategorized

When a Property Manager Outgrows QuickBooks

When a Property Manager Outgrows QuickBooks

You outgrow QuickBooks when you start handling trust accounting, owner statements, owner 1099s, or a HUD chart of accounts.

The four signs you’ve outgrown QuickBooks

The first sign is trust or escrow accounting.

The second is 1099 season. Once you’re the one collecting gross rent and disbursing to owners and vendors, you’re a payer, and payments of $600 or more in rents or services made in the course of a trade or business trigger information reporting (26 CFR 1.6041-1). Tying gross collected to net disbursed, per owner, per year, out of a general ledger built for a single business is where January disappears.

The third is the monthly owner statement. If someone on your team opens a spreadsheet, pulls a transaction report, filters by class, and pastes it into a template twelve times, that’s not accounting. That’s transcription, and it’s where the fee math goes wrong.

The fourth is regulated inventory. HUD-insured multifamily projects have to keep their books under HUD’s prescribed procedures (HUD Handbook 4370.2 REV-1, Chapter 2) and a uniform chart of accounts designed to feed HUD’s own systems (HUD Housing Handbook, Chapter 3), and covered entities file their annual financial reports electronically under uniform financial reporting standards (24 CFR 5.801). You don’t bend a generic chart of accounts to fit that.

Everyone reaches the same workaround first: classes for properties, sub-customers for tenants. It works for a while. Then it stops, in three specific places. There’s no per-unit ledger, only a class filter that breaks the moment a transaction is miscoded. Management fees don’t calculate themselves off collected rent, so someone computes them by hand. And there’s no owner portal, which means statements go out as email attachments. Our Category Archives: Property Management covers the operational side of that transition.

What QuickBooks does and doesn’t do for rentals

QuickBooks is general-ledger software that happens to be used by landlords. It handles debits and credits well and knows nothing about doors. The table below is the feature-by-feature verdict, with a rent-collection add-on in the middle column because that’s the setup most growing managers land on before they move.

Rental accounting functions by tool, from general ledger to purpose-built
Function QuickBooks Online QuickBooks + rent-collection add-on Property management accounting software
Per-unit ledger Workaround via class or customer:job Same workaround Native
Trust/escrow segregation Manual, by bank account Manual Native, enforced
Three-way reconciliation report No No Yes
Management fee calculation Manual journal entry Manual Automatic off collected rent
Owner statements and portal No portal Yes
Tenant rent payments and late fees Invoices only Yes, with autopay Yes, rules-based
Work orders No Varies by add-on Yes, tied to the ledger
1099-NEC/MISC filing Via QuickBooks Yes, owner and vendor
Schedule E category mapping Manual chart of accounts Manual Preconfigured
No In affordable-housing products

Under roughly ten doors you own yourself, QuickBooks plus one bank account per entity is usually enough, and you should build the chart of accounts against the Schedule E expense categories in IRS Publication 527 so year-end is a report, not a project (IRS Publication 527, Residential Rental Property). The moment you collect for a third party, the math changes: you owe someone else’s money, and The $600 information-return threshold for rents has been superseded. The current IRS Instructions for Forms 1099-MISC and 1099-NEC direct filers to report amounts of $2,000 or more for all types of rents in Box 1 of Form 1099-MISC. The $600 figure still appearing in 26 CFR 1.6041-1(a)(1)(i)(B) reflects pre-2026 law that the regulation text has not yet been conformed to; the higher threshold applies to payments made after December 31, 2025 and is inflation-adjusted thereafter. (IRS, Instructions for Forms 1099-MISC and 1099-NEC (rev…) (26 CFR 1.6041-1). Our Category Archives: Property Management Software compares products in that third column.

The real cost of switching, and where it hides

Build your budget from the invoice you will actually pay, not the vendor’s smallest headline number. When a platform is priced per unit per month with a monthly minimum, the minimum is the line that usually governs a smaller portfolio. Then add the charges that sit outside the subscription. The ones that change the total fastest are onboarding, data migration, e-signature packets, screening orders, ACH on resident payments, card processing on rent, owner ACH disbursements, and 1099 e-file charges. That last item belongs in the budget because payments of rents that aggregate to $600 or more to one payee in a calendar year trigger an information return requirement (26 CFR 1.6041-1).

Payments deserve a separate review because the fee can land on you, the resident, or both. Ask whether ACH is absorbed in your software fee or passed through to the resident. Ask what your state allows for card surcharges before you switch card payments on. If you expect real card volume, ask for interchange-plus pricing with the processor’s margin disclosed in writing rather than a flat rate that hides the margin inside one number. Ask for the batch cut-off time too, and whether faster funding is included or separately priced, because funding speed changes cash flow rather than the cost of acceptance. If you want a broader market check while you compare vendors, our Category Archives: Rental Industry Trends 2025 is a useful second read.

The largest cost usually sits on payroll, not the order form. Plan staff time for mapping your chart of accounts, cleaning tenant and owner ledgers, rebuilding bank rules, and parallel-running the old and new systems for one to two closes. Read the contract before the rate sheet. The terms that hurt later are the auto-renewal length, the notice window to cancel, the export format you receive on exit, and whether historical records stay accessible after cancellation. That history matters because owners still need rental income and expense records for tax reporting (IRS Publication 527, Residential Rental Property), and regulated portfolios may need books that remain compatible with prescribed reporting formats (HUD Housing Handbook, Chapter 3).

How to migrate without breaking your books

Set the move for the first day of a fiscal quarter. January 1 is the cleanest choice because you file one full tax year from one system instead of splitting reports and support files across two ledgers. Count backward from that date so you have time to build the new chart of accounts, test a sample rent cycle, and warn owners and residents about any portal or autopay changes. If you manage assisted or insured units, build the accounting structure first so your books stay aligned with HUD-required account formats from day one (HUD Handbook 4370.2 REV-1, Chapter 2) (HUD Housing Handbook, Chapter 3).
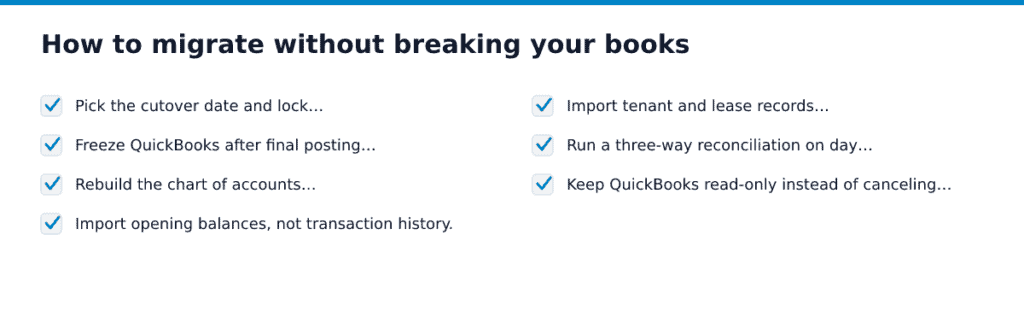
How to migrate without breaking your books. Items: Pick the cutover date and lock…, Freeze QuickBooks after final posting…, Rebuild the chart of accounts…, Import opening balances, not transaction history., Import…
How to migrate without breaking your books Chart: cloudrentalmanager.com
  1. Pick the cutover date and lock it. Use the day before as your last posting day in QuickBooks, and don’t move it once you start resident and owner notices.
  2. Freeze QuickBooks after final posting and reconcile every bank account through the day before cutover. Clear old uncleared items now, because unreconciled transactions come over as noise and bury real opening differences.
  3. Rebuild the chart of accounts in the new system before you import anything. Map each income and expense account to the Schedule E category you report from, and to the HUD Uniform Chart of Accounts if the property is subject to HUD reporting rules (HUD Housing Handbook, Chapter 3).
  4. Import opening balances, not transaction history. Bring in open tenant receivables by tenant, security deposit liability by unit, owner payable or equity by owner, and unpaid bills by vendor, then check that those control totals match your final QuickBooks reports.
  5. Import tenant and lease records with move-in date, deposit held, recurring charges, and any rent escalation schedule. Before any portal switch, send a dated notice to residents and owners, and make sure the new billing descriptor uses a name cardholders will recognize; our Category Archives: Property Management covers the operational side of those notices.
  6. Run a three-way reconciliation on day one and again at the first month-end close. Cash, tenant ledger totals, and deposit liability must tie, and you shouldn’t disburse to owners until they do.
  7. Keep QuickBooks read-only instead of canceling it right away. You need continued access to the records that support rental income, expenses, and depreciation for tax reporting and for the period those records must be kept (IRS Publication 527, Residential Rental Property).

You’re done when opening balances match the final QuickBooks file, the first month closes without unexplained variances, and the first owner statements come from one ledger only.

Choosing between the categories of property management accounting software

One question sorts the field: whose money sits in your bank account. If it’s only yours, you need bookkeeping. If it belongs to owners or residents, you need trust accounting with per-property ledgers. And if any unit is federally assisted, you need a system built around HUD’s prescribed Uniform Chart of Accounts, since HUD requires project books and reports to stay comparable across projects and compatible with its automated systems (HUD Housing Handbook, Chapter 3). None of the vendors named below is a client, advertiser, or affiliate of ours. The categories are the point.

Property management accounting software by category, matched to portfolio type
Deciding criterion
Who owns the cash you hold You do Owners and residents Owners, residents, and agencies
Trust accounting No Yes, with per-owner ledgers Yes, with audit trails
Owner portals and statements Not applicable Standard Standard, configurable
HUD/LIHTC compliance modules No Rarely Yes
Tax output Schedule E Schedule E plus 1099 filing Full GL, agency reporting
Pricing shape Flat subscription Per unit with a monthly minimum Quoted, with an implementation project
Time to first close Days Weeks Months

Category A wins when every door is yours and the year ends on a Schedule E. Category B wins the moment you collect rent you don’t own, and the per-unit minimum is what makes it painful under roughly fifty units. Category C wins when a subsidy contract or a mixed-finance deal puts an agency in the reporting chain, and it loses everywhere else because you’ll pay for depth you never open.

Pick your category first, then request two demos inside it and ask each vendor to run your trust reconciliation on your own numbers. Our Category Archives: Property Management Software has platform-by-platform breakdowns to build that shortlist from.

Frequently Asked Questions

Do I need a separate trust bank account for security deposits?

Yes, in most management setups, security deposits belong in a separate trust or escrow account, and the exact setup turns on your state landlord-tenant law, your brokerage trust-account rules, and any program rules on the property. The accounting issue isn’t just the bank title. Your system should track each tenant deposit as a liability, tie that liability to the cash in the deposit account, and let you reconcile both before you release any money; HUD-insured multifamily projects, for example, use segregated handling of security deposits rather than mixing them with operating cash (HUD, Multifamily Regulatory Agreement, form HUD-92466M) (HUD Handbook 4370.2 REV-1, Chapter 2).

Can I run two entities in one property management accounting system?

Yes, if the system gives each entity its own books inside the same login, with separate bank accounts, ledgers, payables, receivables, and entity-level reports. Don’t rely on classes or tags alone. They organize transactions, but they don’t fix paying a bill from the wrong bank account or issuing a vendor form under the wrong legal entity, and information returns are filed by the person or business that made the payment (26 CFR 1.6041-1).

Judge Commercial Property Software on CAM Reconciliation, Not the Feature List

Judge Commercial Property Software on CAM Reconciliation, Not the Feature List

Hand the vendor one property’s prior-year CAM reconciliation and make them run it live in the demo. Whatever breaks is what you’d have bought.

The Test: Can It Reconcile a Full Year in One Pass?

Common area maintenance reconciliation is the annual true-up between what you billed tenants in monthly estimates and what the property actually spent, with each tenant’s share pulled from their lease’s pro-rata formula. It’s a single calculation that reaches into everything. The general ledger supplies the actuals. Lease abstraction supplies the share, the base year and the exclusions. Expense pools decide which tenants see which costs. Gross-up adjusts variable expenses to a stated occupancy so a half-empty building doesn’t underbill its tenants. Caps limit the increase. Then the whole thing has to land on a tenant statement that a tenant’s auditor can follow.

A feature list tells you none of that. A vendor can check boxes for “CAM tracking,” “lease management,” and “tenant billing” and still be unable to carry a cap forward on a cumulative compounded basis. Residential-first platforms usually bolt CAM on as a report that reads the ledger after the fact. Commercial-native platforms model the recovery as a lease obligation, so the clause drives the number instead of a person retyping it. If you’re comparing tools across both categories, the difference shows up here before it shows up anywhere in Category Archives: Property Management Software.

Two things during the demo tell you the answer is no. The first is an export to a spreadsheet halfway through, because a spreadsheet step means the software doesn’t hold the logic. The second is the phrase “that’s a services engagement,” which means their implementation team does the reconciliation by hand and will keep doing it, at an hourly rate, every year you’re a customer.

The output isn’t only a tenant invoice. Reimbursements a tenant pays toward your operating expenses are rental income to you (26 CFR 1.61-8 — Rents and royalties), and the IRS treats what you receive for the use of the property as taxable income against which rental expenses are deducted (Topic no. 414, Rental income and expenses). A reconciliation you can’t reproduce is a tax figure you can’t defend.

The Nine Lease Clauses the Software Has to Model

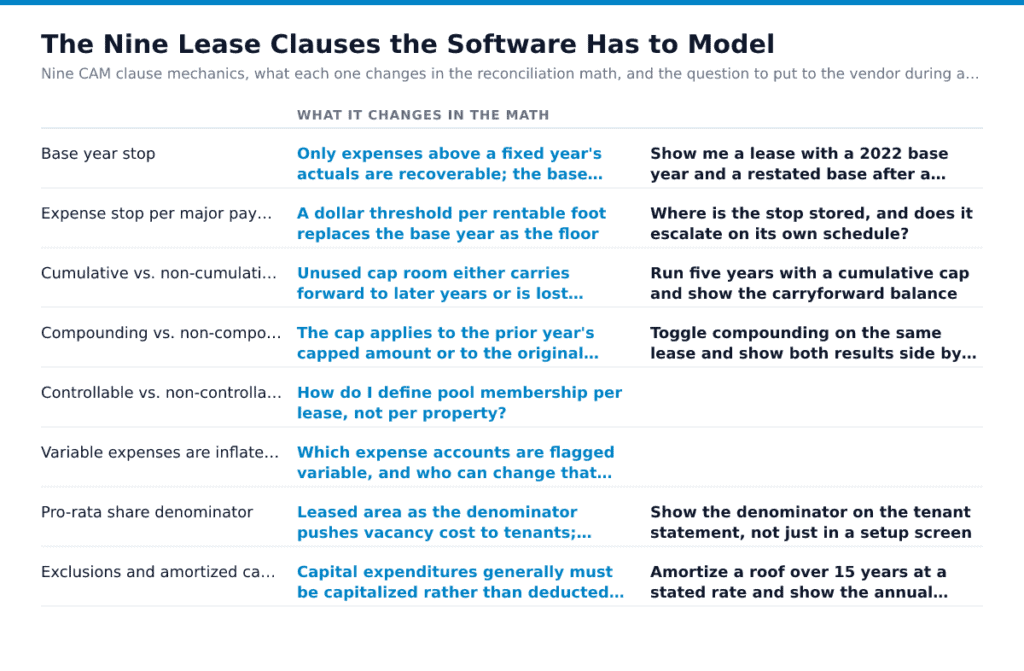
Every commercial lease you sign adds a rule to the math. The software either encodes that rule as data on the lease record or it doesn’t, and when it doesn’t, someone rebuilds the whole calculation in a spreadsheet each January. Take nine clauses to the demo and make the vendor configure them in front of you, on a test lease, while you watch.

Nine CAM clause mechanics, what each one changes in the reconciliation math, and the question to put to the vendor during a demo
Clause What it changes in the math Demo question
Base year stop Only expenses above a fixed year’s actuals are recoverable; the base itself may need restating if occupancy shifts Show me a lease with a 2022 base year and a restated base after a gross-up change
Expense stop per major payment providers foot A dollar threshold per rentable foot replaces the base year as the floor Where is the stop stored, and does it escalate on its own schedule?
Cumulative vs. non-cumulative caps Unused cap room either carries forward to later years or is lost annually Run five years with a cumulative cap and show the carryforward balance
Compounding vs. non-compounding increase limits The cap applies to the prior year’s capped amount or to the original base Toggle compounding on the same lease and show both results side by side
Controllable vs. non-controllable pools How do I define pool membership per lease, not per property?
Variable expenses are inflated to a stated occupancy so partial vacancy doesn’t undercharge occupied tenants Which expense accounts are flagged variable, and who can change that flag?
Pro-rata share denominator Leased area as the denominator pushes vacancy cost to tenants; gross leasable area leaves it with ownership Show the denominator on the tenant statement, not just in a setup screen
Exclusions and amortized capital Capital expenditures generally must be capitalized rather than deducted as a current expense (Topic no. 414, Rental income and expenses), so recoverable capital enters as an amortization schedule with an interest rate Amortize a roof over 15 years at a stated rate and show the annual charge
Anchor and co-tenancy carve-outs Separate expense pools per tenant class; anchors often pay a fixed contribution outside the pool Build two pools on one property and reconcile both in the same run
The Nine Lease Clauses the Software Has to Model. Base year stop, Expense stop per major payment providers foot, Cumulative vs. non-cumulative caps, Compounding vs. non-compounding increase limits, Controllable vs.…
The Nine Lease Clauses the Software Has to Model — Nine CAM clause mechanics, what each one changes in the reconciliation math, and the question to put to the vendor during a demo Chart: cloudrentalmanager.com

Add the audit rights window and the true-up payment or credit deadline as a tenth item, because those are dates the system should be tracking against the reconciliation run. If a clause can only be handled by a manual journal entry, ask who writes that entry next year after the analyst who understood it leaves.

Running the Demo: A Scripted Ninety-Minute Test

Schedule this after you’ve shortlisted two or three vendors, and refuse the generic demo. Bring one property you already know cold: a mixed-use or multi-tenant office building, twelve months of GL detail, and three leases with genuinely different structures, say a gross lease with a base year, a net lease with a cumulative cap, and one with a fixed CAM stop. You already reconciled that property by hand, so you know the right answer. Send the files two days ahead and tell the vendor the demo is a working session, not a presentation.

  1. Have an implementation person, not a salesperson, abstract one of your leases live while you watch, and point to the exact fields holding the cap, the base year and the gross-up percentage.
  2. Load the expense pool, then ask them to exclude one capital item mid-run and re-run the reconciliation without rebuilding the pool.
  3. Change a tenant’s major payment providers footage effective mid-year and confirm the pro-rata share prorates by day rather than snapping to the year-end figure.
  4. Generate the tenant statement and open the backup: every line should trace to GL detail you can attach and a reviewer can follow.
  5. Pull the audit trail for the changes you just made, and ask whether a prior-year reconciliation can be locked against edits.
  6. Ask what renewal pricing looks like, what the termination clause says, and what a full data export costs on the way out.
  7. Confirm the tenant portal displays the true-up and accepts payment for it.

Time the whole pass with a stopwatch and set it against the hours your team currently spends in Excel on that same property. Done looks like a statement you’d mail tomorrow, produced from your data, with backup a tenant’s auditor could open. Anything that ended in “we’d configure that during onboarding” stays on your list of unanswered questions, alongside the other Category Archives: Property Management due diligence you run before signing.

Where the Big Platforms Actually Differ

The decision isn’t which vendor demos best. It’s which tier of product can carry your worst lease, because recoveries you bill are rental income to you the moment the tenant pays them (26 CFR 1.61-8 — Rents and royalties), and a reconciliation your system can’t compute is one you’ll rebuild in Excel every January.

Commercial property software tiers judged on CAM recovery capability
Criterion Enterprise commercial-native (Yardi Voyager Commercial, MRI) Mid-market hybrid (AppFolio commercial, Buildium-class) Accounting-first stack plus lease module Free or low-cost commercial tools
CAM capability to verify in the demo
Realistic portfolio fit Large mixed portfolios with negotiated, non-uniform leases Small office, flex and retail with fairly uniform lease forms Low property count, simple NNN, one or two expense pools A handful of single-tenant buildings
Implementation reality Months, with lease abstraction as the long pole Weeks, if your leases match their template Days, plus your own spreadsheet Immediate, and you own every calculation
Question that disqualifies it Can we get lease and ledger data out in full, on demand? Show me a cumulative cap with carryforward, live How does it handle a base year? Where does gross-up happen?
Pricing shape to pin down Per-unit or per-major payment providers-foot with a monthly minimum Per-unit with a stated floor Per-seat accounting plus module fee Free, until your time is priced

Enterprise wins when a single mis-grossed-up lease costs more than the license. Mid-market wins when your leases are uniform and your AP volume is the real pain. Accounting-first works below roughly a dozen simple NNN properties. We tell clients to read the termination clause and the data-export right before the per-unit price, a point we’ve made across our Category Archives: Property Management Software coverage.

Getting Paid the True-Up

A reconciliation only matters once it turns into money. The true-up invoice is large, irregular, and unfamiliar to whoever opens it, which is the exact profile of a charge that gets disputed and the exact amount you don’t want to pay a percentage on. ACH is the default here. Nacha sets same-day settlement windows and a per-transaction dollar cap (Treasury/Fiscal Service, Federal Government Participation…), so a five-figure true-up may need to go through a standard next-day entry rather than same-day, and your bank’s file cut-off decides which. Card acceptance on a five-figure balance costs a percentage of a number too big to give a percentage of.

If you do take cards for CAM billing, ask two things before you turn it on: what the batch cut-off time is, and whether faster funding is included in your rate or priced as a separate line. Set the billing descriptor to the property name tenants recognize, not the management entity.

Watch the lease deadline too., and the software should flag that date, a practice we track in our Category Archives: Rental Industry Trends 2025. Recovered CAM is rental income when received (26 CFR 1.61-8 — Rents and royalties).

Pull your three largest true-ups from last year and check what each cost you to collect. If any went on a card, price the same invoice as an ACH debit and ask your processor to name the difference in writing.

Frequently Asked Questions

What is the 4-3-2-1 rule in real estate?

There isn’t a single industry-standard 4-3-2-1 rule in real estate; the meaning turns on who is using the phrase and what they are trying to simplify. In commercial operations, it doesn’t tell you anything useful about whether software can bill recoveries correctly or survive an audit. If a vendor reaches for slogans instead of showing lease clauses, charge codes, and approval history, you’re hearing marketing, not seeing proof.

What commercial real estate software is best for brokers?

For brokers, the best software is usually brokerage software, not landlord accounting software. A broker needs deal pipeline, contact history, commission tracking, tour activity, and document workflow, while a property manager needs lease-level billing logic, recoveries, and ledger posting. If your firm does both, judge the stack by the handoff: a signed deal should move from listing to lease record to billing setup without someone retyping suite, term, rent steps, and recovery language.

Is there free commercial property management software worth using?

Free commercial property management software is worth using only for a short pilot on a simple rent roll. The break point is lease complexity: once a lease has expense stops, admin fees, exclusions, or midyear occupancy changes, a free tool usually pushes the real work into spreadsheets and email approvals. Charges a tenant pays under the lease are generally treated as rental income, so your system needs records that tie each billback to the lease and the ledger (Topic no. 414, Rental income and expenses) (26 CFR 1.61-8 — Rents and royalties).

Commercial Lease Software vs Residential Property Management

Commercial Lease Software vs Residential Property Management

Choosing the wrong software can quietly cost you money. A missed rent escalation. An unbilled expense. A lease renewal that slips past its deadline. These mistakes add up fast. And they usually happen when a property manager forces one type of software to do a job it was never built for.

That is the essence of the commercial lease software vs. property management software debate. Both solutions claim to organize your portfolio. Both address rent and tenants, and both address reporting. However, they address different issues. One focuses on the tricky math behind office and retail buildings. The other focuses on apartments, single-family homes, and the beat of the day-to-day leasing of residential property.

This guide breaks down the differences of commercial lease software vs residential property management and helps potential users see what each system addresses best, what companies are top players, and how to match your software to your property. First, let’s explain the fundamental difference.

What Is the Real Difference Between Commercial Lease Software vs Residential Property Management Software?

What Is the Real Difference Between Commercial Lease Software vs Residential Property Management Software

The short answer comes down to lease complexity. Residential leases are fairly standard. A tenant pays a fixed monthly rent. The term usually runs 12 months. The landlord covers most expenses. There are only so many variables to track.

Commercial leases are unlike any others. A single building may house five tenants, with five distinct lease types. One tenant may be on a triple-net (NNN) lease. Another may be on a lease with a clause that adjusts rent based on a percentage of sales. A third may be on a lease that is tied to annual price adjustments based on the CPI. Additionally, each tenant is responsible for a proportionate share of common area maintenance (CAM) costs.

These factors create a great deal of complexity for both tenants and landlords. For this reason, there are specific types of software for managing commercial leases. Compared to software for managing residential leases, these types of software are designed to make more sophisticated computations. Managing a commercial portfolio with a residential tool would quickly highlight the shortcomings of the tool.

Understanding Commercial Lease Software

Understanding Commercial Lease Software

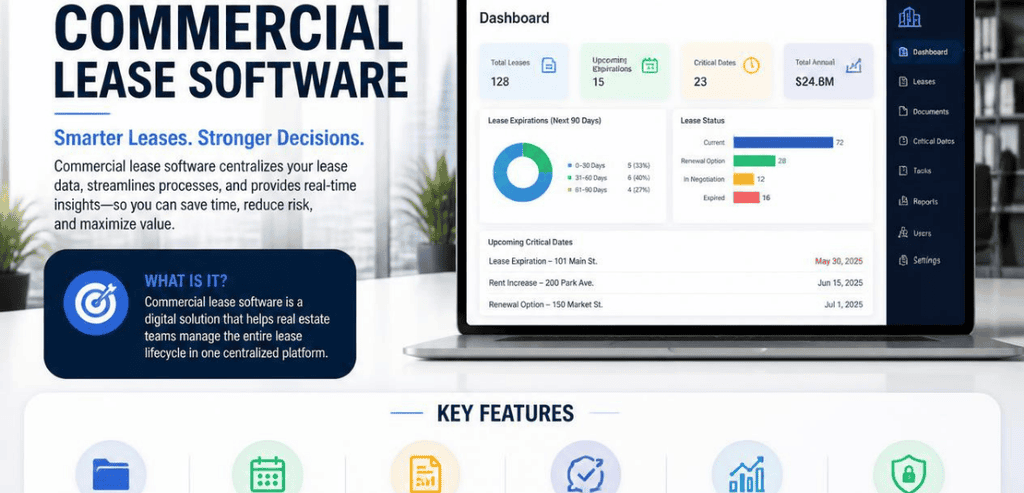
Commercial lease software, sometimes called commercial real estate lease management software, is a specialized platform for nonresidential property. Think office buildings, retail plazas, industrial warehouses, and mixed-use campuses.

It consolidates and offers visibility into lease data. It captures and recognizes lease milestones, key dates, obligations, and tenant-specific language. More importantly, it dynamically calculates notoriously manual and time-consuming spreadsheet tasks.

The most impressive functionality is Automated CAM Reconciliation. This is the annual process of evaluating and reconciling the tenant estimate for operating costs versus actual costs incurred by the landlord. Failing to perform this reconciliation results in a loss of net operating income. Failure to perform a single reconciliation can result in a landlord losing tens of thousands of dollars in unrecovered costs. Best-in-class CAM Reconciliation software performs the math for the tenant’s pro rata share and prepares a clean and easy-to-understand report for the tenants.

Commercial software solutions have the capability to automate and manage renewals, escalations, co-tenancy, and abstractions. Many of the newer solutions offer artificial intelligence (AI) to read leases and determine important dates/clauses with little to no human assistance.

The solution also provides compliance in cases where portfolios or companies are large enough to fall under the regulations set by the FASB for ASC 842. Commercial software is built to automate tasks in compliance with the FASB’s ASC 842 standard.

Yardi

Yardi has been a fixture in real estate software since 1984. Its Voyager platform serves large commercial and mixed-use portfolios that need deep analytics, detailed lease tracking, and enterprise-grade reporting. It is powerful, though it carries a learning curve and custom pricing that fits established firms more than small operators.

MRI Software

MRI Software covers large and complex real estate portfolios. It offers flexible lease administration and strong reporting for office, retail, and industrial real estate. Firms with numerous properties spanning several asset classes regularly select MRI because of its breadth and the ability to integrate other enterprise systems.

STRATAFOLIO

STRATAFOLIO fills a more specific niche. It focuses heavily on CAM reconciliation and financial oversight, and it syncs directly with QuickBooks. Owners who want accurate NNN reconciliations without duplicate data entry find it useful. It suits small and mid-sized commercial operators who need sharper expense recovery without moving to a full enterprise suite.

Understanding Residential Property Management Software

Understanding Residential Property Management Software

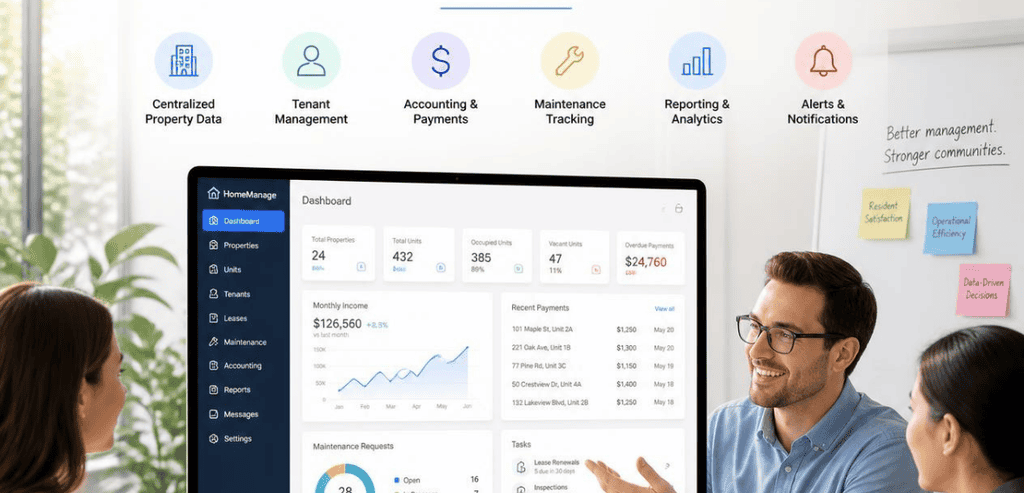
Residential property management software automates the everyday tasks of running rental homes. That means apartments, single-family rentals, small multifamily buildings, and student housing.

The design philosophy is speed and simplicity. Most landlords do not need complexity like percentage rent formulas. They need to be able to fill vacancies, screen tenants, collect rent, and handle maintenance requests. They do not need to be overwhelmed by paperwork.

Because of that, these companies start with lead-to-lease tools. Features allow you to post a listing, receive online applications, run background and credit checks, and sign an accepted lease with an e-signature. Once completed, the software will manage rent collection by ACH or card payments for you, send automatic reminders for payments, store data for you for future tax purposes, and even generate a Schedule E for you. According to the U.S. Census Bureau, there are over 11 million individual landlords, and nearly all of those landlords would benefit from automation at this level.

Automation of maintenance requests is a highlight as well. Tenants enter a request in a portal, and the system creates a work order, and this request is assigned to a vendor. The system manages the request until the task is completed. More advanced systems utilize AI to further automate the system by prioritising and sending appropriate responses to the request.

AppFolio

AppFolio is one of the most widely used platforms among professional residential managers. It bundles tenant screening, digital lease management, online rent collection, and maintenance routing into one interface. It has also pushed hard into AI, with a leasing assistant that qualifies leads and schedules tours. It scales well for growing portfolios, though it is less suited to true commercial work.

Buildium

Buildium is designed for small- to medium-sized teams managing residential or mixed portfolios. It integrates maintenance, leasing, accounting, and operational processes within the same system. It has online application forms, screening, e-signatures, and 1099 eFiling. These features make Buildium a good choice for property managers who are looking for the core features in a system without added complexity.

DoorLoop

DoorLoop is designed for speed and growth. It automates rent collection, screening, accounting, and maintenance in one place. Notably, it stretches into small- to mid-sized commercial and mixed-use work too, including basic CAM tracking. That makes it a flexible bridge for landlords who own a mix of residential and light commercial property.

Commercial Lease Software vs. Residential Property Management: Feature Comparison

Now let’s put the two head-to-head across the areas that matter most.

Lease Structures and Rent Calculations

Residential leases have flat, consistent rent. Commercial leases (NNN, gross, and modified gross) are very different. They contain features like trackers for CPI escalations and percentage rent at the suite level. If your lease does any of that, you can’t use residential tools.

Financial Reporting and Compliance

Residential platforms cater to rent, occupancy, owner statements, and tax-ready accounting. This satisfies most landlord requests. Commercial platforms take more of an enterprise-level approach. They produce reports on the property level and the portfolio level and track CAM caps and exclusions, as well as supporting ASC 842. This level of transparency allows managers to evaluate the performance of an entire portfolio.

Tenant Management and Communication

Residential tenants want easy rent payment and quick maintenance responses. The portals reflect that. Commercial tenant relationships are more contractual. Software must track lease obligations, expense responsibilities, and critical dates for each business tenant. The stakes on a single commercial dispute are usually far higher, so transparency in billing becomes essential.

How to Choose the Right Software for Your Property Type

Start with your portfolio, not the feature list.

Think about what you supervise today and what you think you’ll supervise in the future. Do you run a business that involves renting apartments or single-family properties? A platform designed to manage residential properties will give you everything you need while also saving you money. There’s no sense in wasting your budget on features that you won’t even use.

Automating CAM (common area maintenance) and taking control of your leases should be your biggest focus if your portfolio consists of office, retail, or industrial space. These will protect your net operating income (NOI). A tool designed for residential properties may seem like a cheaper option in the short term, but will become a long-term money pit due to manual errors and unrecovered costs.

Bear in mind everything I’ve discussed, including integrations, onboarding, and the pricing of the tools. The best software will be the most adopted. A complex platform that isn’t used correctly is worse than a simple tool that is used effectively.

Can One Platform Handle Both Commercial and Residential?

Yes, but with caveats.

Vertical mixed-use development projects often include apartments above retail spaces. In the past, owners of these projects have utilized separate property management systems for each of their residential and commercial components. However, many property management systems (PMS) are starting to merge these offerings under the same umbrella, drastically reducing the time and cost involved in managing their assets. MRI Living, Rent Manager, and DoorLoop are some of the more recent entrants into this vertical that combine all components of a mixed-use development under the same PMS.

While systems like these have their advantages, they aren’t always the best fit or follow best practices. Some technologies excel in the commercial domain but not in the residential domain. Misalignment in residential systems often makes it cumbersome to manage complex commercial leases. Misalignment in the reverse creates a similar dilemma. Consider the complexity of your leases and the overall systems you need.

Conclusion

The choice between commercial lease software vs. residential property management is not about which product is better. It is about which product fits your property type. Residential software wins on speed, simplicity, and cost for standard rentals. Commercial lease software wins on the complex financial math that office, retail, and industrial portfolios demand.

Match the tool to the work. A residential landlord does not need CAM reconciliation. A commercial owner cannot survive without it. Evaluate your leases, your reporting needs, and your growth plans first. Then pick the platform built for that reality. Get this decision right, and your software stops being a cost center and starts protecting your bottom line.

Frequently Asked Questions

What Is the Main Difference Between Commercial Lease Software and Residential Property Management Software?

The main difference is lease complexity. Commercial lease software handles NNN leases, CAM reconciliation, percentage rent, and CPI escalations across multi-tenant properties. Residential property management software focuses on standard leases, rent collection, tenant screening, and maintenance for apartments and single-family homes.

Can I Use Residential Property Management Software for Commercial Properties?

You can, but it usually falls short. Residential tools lack CAM automation, lease abstraction, and the complex rent calculations commercial leases require. For a small mixed-use portfolio, it may work temporarily. For any serious commercial operation, a purpose-built platform protects your net operating income far better.

Is Commercial Lease Software More Expensive Than Residential Software?

Generally, yes. Commercial platforms carry more advanced features and often use custom pricing. Residential software frequently offers low per-unit rates or even free tiers for small landlords. The right question is not which is cheaper, but which prevents costly errors for your specific property type.

What Software Supports Both Commercial and Residential Portfolios?

Several platforms serve both, including DoorLoop, Rent Manager, and MRI Living. These suit mixed-use owners who want one system. Just confirm the platform offers deep enough commercial lease management, since some hybrid tools provide only basic commercial features alongside strong residential ones.

Amenity Reservation Systems

Amenity Reservation Rules for Rental Communities with Shared Spaces

Living in a rental community has many pros, but sharing amenities can be a con. With shared amenities like fitness centers and party rooms, you’re sharing with dozens of other members in the community. The cons emerge when the pool gets crowded on the weekend, the clubhouse gets booked for competing birthday parties, and slotted gym sessions conflict with your reserved time. Property managers have implemented reservation systems to avoid conflicts. Knowing how the amenity reservation system works builds community, while ignorance creates friction. This article aims to inform renters and lessors about the amenity reservation systems, including dispute resolution.

Why Amenity Management Is Its Own Operations Category

Why Amenity Management Is Its Own Operations Category

Property management has many components. Different responsibilities and workflows exist for maintenance requests, packages, and lease renewals. The management of amenities stands on its own and deserves specific focus.

Requests for maintenance are reactive and solve a problem for a single resident. Scheduling amenities is proactive and serves the entire community. If a request is submitted to fix an HVAC unit, it serves a single resident. If the pool reservation system is broken on the Fourth of July, every resident has their holiday plans impacted at the community amenity. The focus is on the community.

Property managers who understand the impact amenity management has on community satisfaction will include it as a key component of the overall community experience. Amenity booking policies that are easy to understand, communicate, and enforce increase community satisfaction and lease renewals.

Which Amenities Need Reservations — And Which Don’t

Not all shared spaces require a booking system. The main difference is how much space a booking system helps, and if the space is shared. Some spaces can be designed to help ease access to residents. Some spaces get overcrowded and monopolized by the same people.

Fitness centers, dog parks, seating areas, and co-working lounges are booking-free spaces designed for open and rolling use. A gym for shared use by many people at a time, along with a dog run used by multiple dog owners, is an open-access space. Having a booking system for these spaces is not helpful and may even make the process burdensome.

On the other hand, spaces that are booking-required do help with accessibility. Event spaces and party rooms are good examples. Only one group can use these spaces at a time. Rooftop terraces can be used by more people, but if the seating is limited, then they require a booking system. Areas such as a theater room, golf simulators or pools during busy seasons, and private dining rooms with a tasting area, are spaces of exclusive use that require booking systems.

Some amenities live in a gray zone. A community pool at a large complex might operate on a first-come, first-served basis on weekdays but shift to a reservation model on holidays and weekends. A rooftop deck might be open to the public during the day but require a reservation for catered events after 6 p.m. Good apartment amenity reservation rules account for these nuances explicitly rather than leaving residents to guess.

Reservation Window Limits: Preventing Monopolization of Shared Spaces

Reservation Window Limits

Amenity management involves setting certain rules, including a booking cadence, to prevent misuse of a resource. If a booking cadence is not set, one amenity user can monopolize the reservation system by, for example, booking the party room for every Saturday for the next six months. That type of reservation system is a misuse of a community resource.

A booking cadence is meant to set the maximum advance reservation period. For instance, a booking cadence may specify that a reservation may be made up to 30 days in advance for a particular event space. Reservations for certain community spaces may be booked 45 to 60 days in advance if the space is used for a holiday event. Reservations for community spaces where demand is high, and needs may vary throughout the day, for example, the cabana by the pool or rooftop terraces, may be booked 7 to 14 days in advance.

Frequency caps establish limits on unit-reserving privileges for specific amenities over defined time periods. A reasonable frequency for reserving an amenity would allow one party room per household per month. Highly sought-after amenities may require tighter frequency caps. Frequency caps allow all residents the opportunity to reserve the amenity, rather than allowing the resident who happens to be the fastest clicker to monopolize access.

Equally critical are duration limits. A party room may be reserved for an event with a four-hour duration limit. Reservations for cabanas at the pool may be limited to 3 hours on weekends. Coupled with frequency caps, booking windows, duration limits, and the system of reservation policies, this creates equitable access to amenity reservations.

Property managers should publish these limits prominently in the resident portal, lease addendum, and welcome materials. When residents understand the rules up front, enforcement feels fair rather than arbitrary.

Reservation Fees, Deposits, and Damage Policies

Most amenity reservations in efficient rental communities involve some resident commitment, primarily for reservable event spaces. While this may seem like a money-making mechanism, it is actually an important means of protecting shared spaces and ensuring that residents are respectful when reserving them.

The most common form of a commitment is a refundable security deposit. Residents may pay a fee ranging from $150 to $500 to reserve a space, such as a party room, which would be refunded in its entirety after a post-event inspection confirms it is undamaged and in good order. This method is effective in limiting carelessness and overuse of the space.

In addition, some communities charge a flat reservation fee, which is non-refundable and ranges from about $25 to $100 to cover administrative, cleaning, and maintenance costs. This method is especially common for shorter reservations for spaces that are used more frequently. Further, some communities implement a non-refundable reservation fee and a refundable security deposit as a combination method.

Cancellation policies are just as important. For example, reservations that are held and abandoned at the last minute block other residents from using the space. Depending on the community, a withdrawal from a reservation made 72 hours in advance may yield a full refund, while shorter-notice removals would go without a refund, and same-day reservations would be ineligible for a refund.

How to Handle Disputes When a Reserved Space Is Already Occupied

How to Handle Disputes When a Reserved Space Is Already Occupied

This is the scenario every property manager dreads: a resident shows up at the party room at their reserved time and finds another group already inside with no intention of leaving. Or the gym is so packed that the person with a reserved training session can’t access the equipment they planned to use.

The prevention strategy’s first layer concerns the reservation system. Compared to communities that use sign-up sheets or email bookings, those that use automated systems to issue confirmation codes and display reservations in real time have far fewer issues with double-booking.

Should a booking dispute arise, the procedure for resolving the dispute needs to be set out beforehand. The resident with the reservation needs a direct contact who can confirm the reservation and ask the resident occupying the space to leave. This contact is usually the property management office, a front desk employee, or a community manager on duty. Most residents leave the space when they find out that someone else has a reservation.

The more difficult situations involve residents who, while not formally reserving a space, use it in a way that makes it impossible for other residents to use the space, and who refuse to leave. In these situations, the property manager should document the situation, communicate to both residents the need to comply and the potential consequences, and enforce the consequences for violating the rules if the resident has repeatedly ignored the reservation rules.

Residents who repeatedly occupy a space without a reservation should have consequences that increase in severity. The first consequence should be a written warning. The second should be the temporary loss of their own right to book a reservation. The consequences for continued violations should be addressed through lease enforcement in most jurisdictions. Including this in the lease addendum gives management permission to act without having to devise a solution on their own.

Transparent communication is the most underused tool in dispute resolution. When all residents can see the reservation calendar, misunderstandings decrease. No one can claim they didn’t know the space was booked when the booking is visible to everyone in the resident app.

Technology Platforms That Support Amenity Reservation Systems

Buildium

Buildium is a comprehensive property management platform offering a broad spectrum of integrated tools, from rent collection to maintenance tracking to resident communication. Its amenity scheduling feature allows property managers to define booking rules, request approvals, and send confirmation messages, all from a single dashboard.

Entrata

Entrata has a tenant portal that shows what amenities are available. Tenants can reserve amenities, pay deposits, and access reminders. Calendar sync technology eliminates double-bookings and allows property managers to see how amenities are used in real time across all properties.

Amenity Boss

Amenity Boss is an amenity reservation system for multi-family communities that offers best-in-class features. Those features include configurable booking windows, automated waitlists, deposit processing, and usage reporting. It is a perfect solution for large communities that have multiple high-demand spaces.

Conclusion

Shared amenities are one of the most compelling reasons people choose rental communities over standalone housing. A rooftop terrace, a resort-style pool, or a well-equipped fitness center can genuinely elevate daily life. But those benefits disappear fast when access feels unfair, unpredictable, or constantly contested. Solid apartment amenity reservation rules protect the community experience for everyone — not just the residents who move fastest or push hardest.

Property managers who invest in clear policies, fair limits, reliable technology, and consistent enforcement create communities where residents feel respected. That translates into longer tenancies, stronger word-of-mouth, and fewer headaches on both sides of the lease. Multifamily Executive and the National Apartment Association (NAA) both publish ongoing resources for operators navigating these operational challenges.

Frequently Asked Questions

What happens if two residents accidentally book the same time slot?

A well-designed digital reservation system prevents true double-booking through real-time inventory management. If a conflict occurs due to a system error, the property manager should honor the first confirmed reservation and offer the affected resident priority rebooking or a comparable alternative, such as a complimentary future reservation.

Can a landlord charge a fee for reserving an amenity?

Yes. Landlords and property managers can legally charge reservation fees and security deposits for shared amenities, provided these policies are disclosed in the lease or a separate community rules addendum. These fees must be applied consistently to all residents.

Are amenity reservation rules legally enforceable?

When written into a lease agreement or a lease addendum signed by the resident, amenity rules are legally binding. Violations may be treated as lease violations and subject to the same notice and remedy procedures as other lease terms. Property managers should consult local landlord-tenant law to ensure their policies comply with jurisdictional requirements.

How should a resident respond if someone won’t vacate a reserved space?

The resident should contact property management or the front desk immediately rather than confronting the other party directly. Having the reservation confirmation readily available — in the resident app or as an email confirmation — speeds up the resolution. Property staff are responsible for mediating the situation and ensuring the space is made available to the rightful reservation holder.

Tenant improvements

Tenant Improvements and Build-Outs: A Property Manager’s TI Project Playbook (Commercial)

Tenant improvements are essential to commercial property management because they determine leasing success and tenant satisfaction while enhancing property value. Tenant improvements require methodical planning when they involve establishing new tenant spaces or altering current space configurations, as design, budget, compliance, and execution must be managed together.

Projects lacking a defined procedure face risks of project delays, cost increases, and operational interruptions. Property managers face challenges balancing tenant needs with building codes and budget constraints. Tenant improvement management requires experts to handle more than construction supervision.

The process requires organizations to operate in accordance with lease agreements while administering the tenant improvement allowance work letter and ensuring complete regulatory and operational compliance. The process of tenant improvements requires multiple disciplines, as it needs effective TI project management methods. The tenant improvement checklist establishes clear execution processes that help organizations minimize operational risks.

All project steps, from beginning to end, must be executed exactly until the permit closeout package is completed. The process of integrating sustainability and compliance requirements according to real estate professional standards creates sustainable asset performance improvements.

The guide presents a detailed TI project playbook that property managers can use as a comprehensive resource. Property managers who use this organized procedure will efficiently execute projects by achieving compliance and Treasury cost savings while providing high tenant satisfaction.

Tenant Improvements in Commercial Leasing

Tenant improvements are modifications made to a commercial space to meet a tenant’s operational needs. The changes involve both minor cosmetic updates and extensive structural alterations. The lease agreement usually includes tenant improvements, which both parties negotiate.

Tenant improvements serve as a vital element in tenant attraction and retention from a leasing perspective. A space created by good design enables better functionality and provides improved experiences for tenants. This directly influences occupancy rates and long-term lease stability.

Tenant improvements require operational coordination among various stakeholders who must work together to complete their tasks. The stakeholders include property managers, tenants, architects, contractors, and regulatory authorities. The project requires each party to contact other parties through which essential information will flow.

Tenant improvements must comply with building standards and regulatory requirements. The regulations include safety codes, accessibility regulations, and sustainability considerations. The requirement must be met to avoid project delays and penalties.

Property managers use their knowledge of tenant improvement scopes and significance to develop strategic project plans that lead to successful outcomes.

Building a Tenant Improvement Checklist for Consistent Execution

To help ensure you complete the project efficiently, use a checklist to provide a structure for project management. A good checklist will help ensure that you do not miss any major steps in your project, which can lead to delays or increased costs.

A good tenant improvement checklist will have the following items:

  • Review of lease and TPIP (Tenant Improvement Allowance Work Letter Analysis).
  • Define scope and get design approvals.
  • Develop a budget and cost tracking.
  • Select and procure a contractor.
  • Obtain all required permits.
  • Monitor construction and control quality.
  • Complete the final inspection and permit closeout package.

Clearly define who is responsible for each of the above steps, ensuring someone is held accountable for completing them consistently throughout your projects.

In addition, your checklist should be flexible enough to accommodate project-specific reasons outside the standard guidelines. Adjustments can be related to the type of tenant, the type of building, or tenant-specific requirements, to respond to variations in how your property has been configured.

Interpreting the Tenant Improvement Allowance Work Letter

The tenant improvement allowance work letter functions as an essential document that establishes both financial obligations and operational duties of the involved parties. The document establishes the methods for financing and executing tenant improvements.

The document includes information on expenses eligible for reimbursement, the required timeframes, and the procedures for obtaining authorization. The terms of the agreement must be understood by everyone involved to achieve successful TI project implementation.

All project activities require property managers to guarantee their compliance with the established work letter. The project team will encounter legal conflicts and unplanned expenses when they fail to follow established procedures. 

Establishing clear communication procedures with tenants will help the organization prevent potential misunderstandings. The work letter contains additional provisions that describe how to handle situations when costs exceed the initial budget.

Identifying the party accountable for extra costs is a vital component of budget development. The process establishes budget management procedures that prevent budget overruns.

Property managers can achieve two goals through their careful analysis of the tenant improvement allowance work letter, which establishes project expectations and controls project spending.

Planning and Budgeting for Tenant Improvements

Successful tenant improvements require effective planning and budgeting. Projects need a financial strategy, which should be developed before work begins. The planning phase starts with project scope definition, which includes tenant requirements, design specifications, and compliance needs.

Accurate scope definition ensures realistic budgeting. Cost estimation is an essential element of the project. Property managers need to account for all construction costs, together with design fees, permits, and contingency expenses.

Including a contingency buffer will provide funding for unplanned expenses. The budget alignment with the tenant improvement allowance work letter guarantees financial transparency. This system prevents disputes by clarifying which party is financially responsible.

Budget tracking must be conducted regularly. The project expense monitoring process enables early detection of budget deviations, which triggers the implementation of corrective measures. Property managers can achieve cost control through thorough planning and budgeting, enabling them to complete tenant improvements within budget.

Managing TI Project Management From Design to Construction

TI Project Management is the management of the tenant improvement project throughout the tenant improvement project’s lifecycle, from beginning to end. Coordination, communication, and attention to detail are all integral to successful management.

Within the tenant improvement project’s design phase, design layout, construction materials, and the permitting process should be developed by all parties involved in the tenant improvement project. Tenants, engineers, and property managers meet the functional specifications and regulatory requirements of the tenant and improvement project.

During the tenant improvement project’s construction phase, Property Managers are responsible for maintaining contractor timelines and monitoring the contractors’ workmanship by conducting regular site visits to identify any potential construction delays and maintaining the overall tenant improvement project’s schedule.

Communication with the stakeholders during each of the phases of a tenant improvement project is very important. Keeping everyone in the loop will reduce the likelihood of any misunderstandings and will ensure that everyone is on the same page. A clear reporting structure is also an important part of being able to make timely and appropriate decisions.

Risk management is also a very important part of tenant improvement project management. Identifying risks at an early stage of the project and developing risk mitigation strategies will help reduce the risks of delays in the construction schedule and of increasing the total budget costs.

Through the utilization of effective tenant improvement project management practices, Property Managers can successfully provide their clients with tenant improvements (TI) in a timely and cost-effective manner.

Navigating Permits and Regulatory Compliance Requirements

Tenant improvements require obtaining permits and meeting compliance requirements. Projects must meet local building codes, safety standards, and accessibility regulations before construction can begin. The permitting process requires the submission of design plans for approval by regulatory authorities.

The step requires significant time to complete, so early submission is vital to maintaining project timelines. Property managers must ensure that all required permits are obtained before construction starts.

The company faces penalties, including fines, operational delays, and work stoppages, due to its failure to fulfill this obligation. Compliance requirements exist beyond the initial approval process. The construction process demands inspections at multiple points to verify compliance with regulations.

Environment and sustainability aspects are gaining higher significance in the present times. The use of energy-efficient designs adds design value, follows industry standards, and increases property value.

Coordinating Contractors and Vendors Effectively

The contractor coordination process is a fundamental component of completing tenant improvements, and property managers must ensure that they only hire contractors who can work together. When selecting contractors, property managers should assess their experience and qualifications as well as obtain references for their work.

Selecting reputable contractors assists in avoiding issues with product quality and project delays. The contract documentation, including the scope of work for the project, forms the minimum requirements for the contract. It sets clear expectations regarding each party’s obligations and helps to mitigate potential conflicts.

A clearly defined agreement ensures the responsibilities of all parties are readily apparent through their respective roles. The construction delivery method necessitates that the construction teams communicate regularly with their contractors throughout the construction process. Regular progress meetings and project updates will keep the teams and the contractors informed of the project’s status while also resolving any issues.

Vendor schedule management creates a structure that allows for the correct sequence of execution of construction activities. Proper coordination methods enable successful systems that help to avoid delays (bottlenecks) and improve the operational efficiency of the construction process.

Monitoring Construction Progress and Quality Control

Construction progression monitoring is vital to keeping timelines on point and maintaining quality. Property managers must supervise project execution to identify potential concerns when they arise and address them as they occur.

Site visits will provide visibility into construction progress and craftsmanship. Site visits will confirm that the completed work meets the design specifications and quality standards.

Tracking milestones to compare actual progress against planned schedules will allow management to discover areas of delay and initiate corrective measures.

Incorporating quality control measures into construction will ensure that materials, craftsmanship, and compliance specifications are met throughout the project’s lifespan.

Documentation is a key step in project management, along with written documentation supporting inspections, changes, and approvals. By creating a written record, you are providing each person involved with a way to hold themselves accountable to one another and to the project manager.

Completing the Permit Closeout Package and Final Inspections

The permit closeout package is the final step in tenant improvements. The package confirms that the work was completed in accordance with all relevant regulatory standards.

The package includes inspection reports and certifications, which are combined with as-built drawings. The documents serve as evidence that the project complies with all relevant standards.

Regulatory authorities conduct final inspections to verify that all requirements have been fulfilled. Property managers must resolve all issues before they can request inspections.

Final project work needs to obtain complete project work. Tenants will lose access to the space if the necessary closeout documents remain uncompleted.

The process of organizing and submitting the permit closeout package should be efficient to ensure a seamless transition from construction to building occupancy.

Aligning Tenant Improvements With Sustainability and Lease Standards

The requirements for tenant improvements need to be fulfilled through sustainability-related standards. Green buildings provide higher-performing long-term assets with increased tenant satisfaction. Organizations achieve lower operational expenses through the implementation of energy-efficient systems, the use of sustainable materials, and waste reduction methods.

The actions taken by the organization fulfill both environmental objectives and legal requirements. All tenant improvements will achieve standardization through their required compliance with lease terms because this requirement applies to every area of the property.

The project contains design requirements together with material specifications and operational requirements. Sustainable leasing practices will be defined through industry standards that lease standards will use for their application. 

Financial benefits will continue to flow into the property through the use of these principles, together with tenant improvements. Property managers who implement sustainability practices together with lease compliance will finish their projects according to existing standards while increasing property value.

Avoiding Common Pitfalls in Tenant Improvement Projects

Challenges in the proper management of tenant improvements can arise from multiple issues. To minimize the likelihood of making potentially costly mistakes, it is important to recognize some of the more common errors that property managers often make. Specific areas of concern can include:

  • Unable to execute the tenant improvement checklists correctly and completely.
  • Failure to correctly interpret the summary of the tenant improvement allowance construction requirements.
  • Not obtaining timely permits or approvals results in avoidable construction delays.
  • Inability to coordinate the contractor(s) on time.
  • Failure to adequately monitor and provide quality assurance throughout the construction process.

The best way to avoid the pitfalls mentioned above is with qualified proactive planning and outstanding project management. Regular reviews and clear lines of communication will help to quickly identify and resolve issues.

Utilizing proven expertise will also provide better results. By working with qualified and experienced individuals who possess a complete knowledge of design, construction, and compliance, the chances of project success will increase.

Scaling Tenant Improvement Processes Across Portfolios

The management of tenant improvements requires processes that can grow to handle multiple properties. Implementing standard processes alongside technological solutions enables businesses to achieve their operational objectives. 

The use of centralized systems enables property managers to oversee their projects and budget plans and document materials across their entire property portfolio. The system enhances operational visibility and improves coordination between departments.

Standardized tenant improvement checklists create a framework that enables organizations to maintain operational uniformity. Implementing identical procedures across properties reduces operational differences, leading to better performance.

Automation enables organizations to achieve their business goals by improving operational efficiency. The organization uses tools to automate its operational tasks through workflow management, approval processes, and performance assessment. Implementing standardized operational procedures enables organizations to achieve their operational objectives.

The need for standard process training becomes critical when organizations handle extensive portfolios that involve various operational partners. The development of effective tenant improvement procedures enables property managers to manage their extensive property portfolios with complete confidence.

Conclusion

Managing commercial real estate is heavily dependent upon the need for tenant improvements that require precision in their planning, coordination, and execution from design development through to final closeout of the project’s permit package.

Projects that do not have a formalized methodology to manage the project will experience challenges, causing delays, increased costs, and compliance issues. The property manager uses a complete tenant improvement checklist to develop standardized procedures to ensure consistency of the project during their execution. 

The TI allowance works letter defines the financial parameters for TI projects; however, effective TI project management techniques allow for projects to be executed economically. Incorporating sustainability considerations into a project will enhance the asset value during the life of the asset and demonstrate compliance with industry standards.

Tenant improvements will require technical proficiency, operational discipline, and strategic planning. Property managers utilize structured methods to provide maximum value and efficiency in the execution of tenant improvements for their institution.

FAQs

What are tenant improvements in commercial real estate?

Tenant improvements refer to the permanent modifications that landlords implement on commercial properties to create spaces that fulfill their tenants’ needs. The alterations include changes to the building layout and interior design elements, as well as the installation of new systems.

What is a tenant improvement checklist?

A tenant improvement checklist establishes a systematic process for executing a project, which starts with planning and ends with project completion while maintaining consistent and effective project execution throughout. 

What is a tenant improvement allowance work letter?

The lease document describes the process for funding tenant improvements, including details on the allowance amount and permitted expenditures, as well as the duties of all parties involved. 

What is included in a permit closeout package?

A permit closeout package contains final inspection documentation, certifications, and all records demonstrating that the project meets all regulatory standards. 

Why is TI project management important?

The successful management of TI projects enables companies to finish their tenant improvements on schedule and under budget while meeting all required standards, for better project results through risk assessment methods.

HOA Reserve Studies

HOA Reserve Studies and Inflation-Adjusted Capital Planning: Turning Reserve Reports Into Action

HOA restrictions require community associations to closely examine the effects of inflation and how it affects the community’s overall operations. Historical models used to plan reserve funding have changed over the past several years due to material price escalations, labor-force reductions, and general economic volatility. 

Associations that rely on outdated assumptions risk having to fund their reserves through unexpected special assessments. Creating a funding plan for reserves based on a reserve study report is difficult for many boards of directors. This leads to deferred maintenance issues, financial instability, and general homeowner discontent.

Today’s reserve planning requires future funding assessments, including adjustments for inflation, to maintain and improve their assets and project replacement costs. The reserve study standards established by CAI assist associations in meeting their expectations by establishing a standard methodology.

This article provides a step-by-step guide to turning HOA reserve studies and inflation insights into actionable strategies. It provides the best practices for establishing reserve study schedules, updating reserve studies, and the fundamental principles of HOA.

Understanding HOA Reserve Studies and Inflation in Capital Planning

The connection between HOA Reserve Studies and Inflation forms a fundamental element of contemporary capital planning methodologies. The reserve study analyzes both the current condition of community assets and their projected operational lifespans. The study predicts future costs needed to fix or replace all system parts during their operational lifespan.

The cost estimates are directly affected by inflation. The expenses for construction materials, labor, and equipment costs show annual growth. The reserve projections become inaccurate because they require inflation adjustments that researchers did not include. This situation results in insufficient funds because organizations require extensive repairs.

An effective reserve funding plan needs to include inflation projections when creating financial strategies that extend into the future. The plan guarantees future expenditures will match actual market conditions. Associations that ignore inflation risk are significantly underestimating their financial needs.

The process of increasing funding requirements is driven by inflation. Organizations need to adjust their monthly dues and reserve funding based on their current financial standing. The relationship between HOA Reserve Studies and Inflation helps boards develop stronger financial planning methods that protect their assets over extended periods.

What a Reserve Study Includes and How to Interpret It

The reserve study provides a comprehensive evaluation of the physical and financial resources an association maintains. The study typically presents three main elements: component inventory, condition evaluation, and financial forecasting. The decision-making process requires understanding these elements, as they are essential to achieving successful outcomes.

The physical analysis identifies major components, including roofs, elevators, and HVAC systems. The assessment process evaluates each component to determine its remaining useful life and necessary replacement expenses. The reserve funding plan establishes its base using this data.

The financial analysis provides two main outputs: future expense predictions and recommended funding amounts. The analysis process includes assessing inflation rates, interest rates, and funding methods. The projections enable boards to prepare for their future financial requirements.

A reserve study requires interpretation by examining its essential measurement points. The funding percentage, together with cash flow projections and recommended contributions, enables assessment of organizational financial performance. Boards require regular assessments of these metrics to confirm their progress toward achieving established targets.

Associations need to understand reserve study interpretation because it enables them to make informed choices while preventing financial planning that depends on reactions.

HOA Reserve Study Frequency and Why It Matters

The frequency of HOA reserve studies is critical to maintaining accurate financial projections. Industry standards recommend conducting a full reserve study every three to five years. However, annual updates are equally important for adjusting financial assumptions.

Frequent updates ensure that cost estimates remain aligned with current market conditions. Inflation, material costs, and labor rates can change rapidly. Without regular updates, projections may become outdated and unreliable.

Additionally, the frequency of reserve studies affects compliance with CAI reserve study standards. Many guidelines emphasize the importance of periodic reviews and updates. Associations that follow these practices demonstrate strong governance and financial responsibility.

Operationally, regular updates support proactive planning. Boards can identify potential funding gaps early and adjust contribution levels accordingly. This reduces the likelihood of unexpected special assessments.

By maintaining an appropriate reserve study update schedule, associations can ensure that their financial plans remain accurate and effective.

Building a Reserve Study Update Schedule That Works

An organized reserve study update plan is a key component of creating an effective capital budgeting process. It should have defined timelines associated with both complete reserve studies and interim updates to maintain accuracy in the long run.

Typical update schedules include:

  • A complete reserve study every 3-5 years.
  • An annual financial update that takes into account inflation and any other cost increases.
  • Regular preliminary inspections of all significant components of the association.
  • An annual review of any assumptions made in the existing reserve funding plans.

All updates will use the latest market-based data, including, but not limited to, cost estimates, inflation rates, and condition reports for each major component. The accuracy of this data will ensure that you can develop reliable projections.

The update schedule should also coincide with your budget preparation cycle, so you can promptly adjust your required reserve contributions and reduce your risk during the budget preparation process.

Responsibility for executing updates should be clearly defined among the board of directors, property management, and the reserve specialist. They must work cooperatively to complete these updates promptly.

By following an organized reserve study update plan, associations can maintain accurate and actionable financial plans.

Developing a Reserve Funding Plan That Reflects Inflation

The reserve funding plan uses reserve study data to develop executable financial plans. The plan needs inflation adjustments to maintain adequate funding throughout the project. The inflation planning process requires organizations to increase their budget estimates to account for anticipated future price increases. The process establishes future financial requirements that can be met through actual budgetary capabilities. The associations will experience funding shortages if this adjustment does not occur.

Inflation needs to be included in all contribution strategies. Organizations must regularly assess their monthly dues and reserve allocations to ensure these expenses align with their upcoming financial obligations. People find gradual increases easier to handle because they are less disruptive than sudden changes.

Contingency factors need to be part of funding plans. The budget is disrupted by sudden expense increases and delays in project completion. The plan becomes more flexible through the implementation of built-in flexibility elements.

Associations can achieve financial stability through their reserve funding plan, which uses inflation-based funding methods to prevent them from having to make emergency financial decisions.

Aligning With CAI Reserve Study Standards for Best Practices

The CAI reserve study standards outline best practices for conducting and maintaining reserve studies, ensuring that all financial forecasting is accurate, transparent, and consistent. Also, the CAI reserve study standards address the need for the following:

  • Regularly updating reserve studies to reflect the actual conditions and costs at the time of performing the reserve study.
  • Developing a complete inventory of reserve components and assessing the conditions of each component.
  • Management of current operating and capital expenses using financial projections and reasonable assumptions for those projections.
  • Collaboration between boards, managers, and professionals.

Adhering to the CAI reserve study standards will create greater credibility and trust between the association and its members and provide useful, actionable information through reserve studies rather than being a report of historic events.

Finally, the CAI Reserve Study Standards emphasize aspects of inflation. Accurate projections of future costs must be based on realistic forecasts and assumptions of future inflation.

Following the standards outlined in these guidelines will promote long-term financial stability by helping associations maintain their capital expense funding, thereby preventing future capital expense shortfalls. The boards can improve the overall effectiveness of their reserve planning processes by utilizing the CAI reserve study standards.

HOA Reserve Fund Accounting and Financial Transparency

Accounting of HOA reserves is a vital part of HOA finances, ensuring proper tracking, allocation, and reporting on how these funds are used. Trust is built on accounting transparency, which leads to informed financial decisions.

​Reserve funds should be kept separate from operating accounts. This will prevent reserve funds from being used for operating expenses and ensure they remain available for capital expenses. Following sound accounting practices also helps ensure compliance with applicable laws.

It is also important that financial statements provide clear information regarding reserve fund balances, reserve contributions,s and reserve fund expenditures. This allows both the board and members to have a clear idea of the association’s financial position. Routine reporting enables the Board to monitor the associationis performance and identify potential issues.

When preparing the required budgets for the association and evaluating funding for future projects, inflation must be considered in the association’s accounting practices. When projections and contributions are adjusted, the financial statements’ accuracy is maintained.​

Turning Reserve Reports Into Actionable Maintenance Plans

The value of reserve reports is realized only when the information is translated into maintenance action plans. The information contained in reserve reports should serve as the basis for boards’ prioritization and resource allocation for a project.

The first step in creating the necessary action plan is to identify which components should be considered a high priority. Specifically, items with a shorter remaining useful life or deemed to pose a higher risk should be given priority for addressing. This will help reduce the risk of costly failures and ensure the safety of residents.

The next step is to coordinate the maintenance schedule with the reserve study schedule to maximize efficiency and minimize the disruption to residents. Generally, scheduled maintenance costs less than reactive maintenance.

Communication is also critical. Property owners are more likely to support funding for upcoming projects when they are informed about them before their commencement. Providing this level of transparency will build trust and reduce resistance among property owners to expenditures they must pay for as a result of the execution of formal reserve reports.

By creating actionable plans based on the information in the reserve report, associations will be able to improve the management of their assets and financial position.

Managing Inflation Risks in Long-Term Capital Projects

When planning long-term capital projects, inflation-related uncertainty may arise, and managing it requires proactive planning and flexible strategies. One way to address this uncertainty is to incorporate conservative inflation assumptions into forecasts, thereby allowing for unexpected cost increases.

Associations should regularly review their inflation assumptions to ensure that they are accurate. Another effective strategy for reducing risk in capital projects is to implement phased project planning, dividing them into smaller phases. This allows recalibrating costs based on current market conditions, increasing flexibility, and providing better cost control.

In addition, vendor relationships can help mitigate inflation risks by enabling you to negotiate long-term contracts or establish preferred vendor arrangements, both of which help stabilize costs amid market fluctuations. By effectively managing inflation risks, associations will retain control over capital planning and mitigate the risk of unanticipated financial impacts.

Communicating Reserve Planning Decisions to Homeowners

Homeowners effectively plan their community’s reserves. They must also understand how their reserve study impacts inflation and how good communication is the foundation upon which trust is built. Thereby enabling residents to feel comfortable supporting their board of directors in making financial decisions. It will be helpful for the board to clearly communicate how the reserve study will aid in budgeting and project planning.

Regular updates regarding the status of their projects or their association’s finances give residents a sense of accountability, actively engage residents, and enhance confidence in the community’s success. In conjunction with more frequent updates to homeowners, education creates a better understanding of the reserve fund by teaching homeowners the mechanics of how it is funded.

This will be particularly important if the homeowner chooses to change his/her contribution toward the reserve fund. Through improved communication and understanding of the reserve fund, the association involved increases its likelihood of successfully implementing the reserve plan.

Common Mistakes in Reserve Planning and How to Avoid Them

The operational difficulties and financial problems that result from associations’ planning errors need to be studied because they create operational problems and financial difficulties. The following common mistakes occur in most situations:  

  • Reserve study cost estimation requires inflation to be included, but this requirement remains unfulfilled.
  • The reserve study update requires new information, but the organization has not yet conducted the required updates.
  • Boards establish reserve contribution levels, which lead to underfunded reserves because they lack an understanding of actual funding requirements.
  • The organization does not follow the Community Associations Institute’s Standards for Reserve Studies.
  • The organization fails to properly account for investment returns held in reserve funds.  

Sound management, with regular assessment, makes reserve planning successful by preventing these common mistakes. The board should use three types of financial information, which are precise, open, and stable, to guide its planning activities. The organization will achieve better outcomes through partnerships with reserve experts who possess professional knowledge.  

Reserve specialists will apply best industry practices while maintaining compliance with all required operational standards. Associations can achieve better financial results and improved reserve study planning by handling these mistakes.

Scaling Reserve Planning for Larger Associations

As associations grow, they become more complex in their reserve planning. Associations with multiple assets, larger budgets, and more complex property management will require greater sophistication in terms of both strategy and systems.

Centralised data management is a necessary tool that consolidates data related to a reserve study into a single point of reference. Therefore, all stakeholders involved in developing a reserve study will have access to consistent, timely, and coordinated information.

The larger associations require more frequent updates to their reserve studies due to their larger number of assets and the need to be monitored more frequently. As a result, larger associations may choose to adopt a revised reserve study update schedule to keep their reserve studies as relevant as possible.

Technology can also improve efficiency for day-to-day operations. For instance, the use of financial management systems and analytics software helps to streamline the operational processes and provide supporting reporting.

The potential for larger community associations to employ dedicated staff positions for financial and asset management enables greater consistency in oversight in this area. When larger associations utilise scalable reserve planning strategies, they will be able to maintain control over their reserves and, ultimately, long-term financial stability.

Conclusion

Inflation and HOA reserve studies are fundamental to how associations manage their capital today. As the economy changes, so do methods of developing and implementing reserve fund plans. Therefore, any change in the way we forecast reserve funds must also account for inflation.

This is possible through both inflation forecasts and the establishment of a structured funding plan to ensure long-term financial stability. An established schedule for updating reserve studies ensures the consistent maintenance of current data and encourages adherence to CAI Reserve Study Standards.

It is imperative to convert reserve fund reports into structured action plans if the association is to effectively manage its assets. Communicate effectively with its members about the association’s maintenance needs, the risks associated with inflation, and how to make well-communicated, effective decisions. 

By incorporating both HOA Reserve Studies and Inflation into a financial strategy, associations can minimize risk, avoid unforeseeable expenses, and contribute to the long-term viability of the community. Following the outlines provided in this writing, can more effectively turn reserve studies into actionable, reliable action plans that can be executed now and into the future.

FAQs

1. What are HOA Reserve Studies, and why are they important?

HOA Reserve Studies help communities assess their existing assets and estimate future maintenance costs. The studies serve a vital function by helping communities with their financial planning while avoiding unexpected financial obligations.

2. How often should an HOA reserve study be updated?

The standard practice for HOA reserve studies requires complete assessments every 3 to 5 years, with yearly updates to reflect inflation and changing conditions.

3. What is a reserve funding plan?

The reserve funding plan establishes the procedures for an association to raise funds to finance upcoming maintenance and replacement projects. The system establishes financial stability, enabling emergency readiness.

4. How does inflation affect HOA reserve planning?

The combination of inflation and material cost increases leads to rising expenses, further increasing future costs. The process of adjusting reserve studies to inflation rates yields precise financial forecasts.

5. What is HOA reserve fund accounting?

The process of HOA reserve fund accounting requires organizations to monitor their reserve funds while keeping those funds distinct from their operational budget. The system provides visibility into financial operations while ensuring that funds are distributed correctly.

Condo Financing

Condo Financing Readiness: Reserve Studies, Structural Integrity Signals, and the Documentation Buyers Need

Condominium finance has radically changed over the past few years because of regulatory oversight, GSEs, and notable structural failures.

The FHA, Fannie Mae, and Freddie Mac have all established eligibility guidelines for purchasers, lenders, and homeowner associations (HOAs). Reserve funding, structural soundness, and in-depth project documentation are the building blocks.

Understanding these requirements is vital in determining whether a condo is warrantable and also certifies the loan approval process. This article goes over everything you need to know to be prepared for condo financing, from reserve funding to structural safety indicators to documentation requirements.

Condo Project Eligibility: The Foundation of Financing

The organizations want to see if a condo project meets certain guidelines before they lend. They want their lender to perform a thorough analysis of the project prior to loan approval to show that the property is financially sound, adequately funded, and soundly constructed.

They look at the financial condition, insurance coverage, governance structure, and financial health of a condo, not one thing. Even if there are some excellent individual buyers, a condo project may be ineligible if there are no reserve funds and/or legal actions and/or unpaid maintenance.

Importance of Reserve Studies in Condo Financing

Reserve Studies: A Look Inside the Condo Project’s Financial Future

The reserve study is an essential component of a financial viability analysis of a condo project. The study, like a financial statement, evaluates the condition of the major common elements (including roofs, elevators, plumbing, and structural), estimates the replacement and operating costs of those elements and outlines a financial roadmap. A solid plan protects the HOA from having to rely on costly special assessments.

Reserve studies also give a lender a view of the project’s prudent management and control. Lenders usually expect to see a current reserve study that reflects the actual level of reserve funding, as defined in Fannie Mae’s Reserve Study requirements. The absence of reserves indicates financial problems. A gap between the recommended and actual reserve funding levels is even worse. It signals financial distress and jeopardizes project eligibility.

Structural Integrity and Deferred Maintenance: Key Risk Indicators

Condo finance has been under scrutiny for some time now because of its emphasis on structural integrity. Lending teams are looking at projects with obvious signs of deferred maintenance, if not projects on the brink of needing some major repairs, with an increasing level of scrutiny. The issue is gaining serious traction in the industry and is being linked to larger issues regarding construction quality and project sustainability.

Deferred maintenance, such as a patchy roof, aging infrastructure, or unfinished structural questions, can be indications of an underfunded or poorly managed HOA. This is often accompanied by special assessments, which only adds to the financial burden of the house owners. The lender may be deemed ineligible for the position because of the increased risk of reviewing the project.

It could be the engineering reports, inspection findings, or current repair work that are the discussion points that influence a lender’s decision. Lack of clarity on financing or timelines means that the funding could be delayed or even not approved, even if the repairs are already underway. So protecting structural integrity is not just about safety; it’s also a solid prerequisite for securing a mortgage.

Fannie Mae Condo Requirements and the Full Review Process

The most common criteria for condo financing are those established by Fannie Mae. The Full Review Process is a thorough assessment tool used by lenders to establish if a project is eligible. It includes a comprehensive review of the financial and legal structure, occupancy and physical condition.

The financial viability of the HOA, including delinquency and reserve funding, is also a part of the review. High delinquency and/or reserves may indicate a high-risk project. Many developers and lenders use reserve studies to assess whether the HOA reserves and financial management are adequate to cover maintenance needs in this environment.

Disqualifying characteristics, such as serious legal issues and major repairs, are also identified during the full review process. Fannie Mae uses a combination of financial, legal, and physical reviews to ensure that well-managed, viable projects qualify for financing.

FHA Condo Approval Requirements: Expanding Buyer Access

The Federal Housing Administration (FHA) is critical to homeownership, especially for purchasers with smaller down payments or less common financial profiles. FHA loans are only available for approved condominium projects. That makes eligibility a key concern. Developers and HOA boards must verify that the property is approved by the FHA.

A project must meet requirements for financial stability, occupancy, and insurance coverage to be approved. 

The FHA requires that projects be listed on its authorized condominium database so that lenders can easily verify eligibility. The purpose of the approval process is to protect both the borrower and the lender by ensuring that the underlying property meets minimum requirements.

FHA clearance can significantly strengthen a project’s market appeal, because it gives access to a larger pool of potential purchasers. Some purchasers will not be able to secure financing without FHA clearance, which would limit demand and affect real estate prices.

Freddie Mac Condo Standards: Aligning with Market Stability

Freddie Mac’s condo standards are “virtually identical” to Fannie Mae’s condo standards. Both emphasize financial soundness, sufficient reserve funding, and building soundness. Freddie Mac has made a few updates to align better with the lenders and to provide guidance throughout the review process.

The emphasis on these standards highlights the importance of sound financial management and appropriate documentation. Freddie Mac’s mission is to promote long-term stability in the housing market and reduce risk through prudent loan underwriting and quality maintenance and resourcing of projects.

By meeting Freddie Mac standards, there are increased opportunities for consumers to purchase through affordable loans. Freddie Mac’s standards also help to illustrate the importance of sound financial and operational practices to condo projects.

Documentation Requirements: What Lenders Need to See

Condo financing is all about having the right documentation in the right place. Lenders use various documents to determine whether a project is eligible for financing and what these documents say about the project’s financials and condition.

The reserve study is probably the most important of all because it is forward-looking and tells the lender about maintenance needs and the funding plan. The financial statements, such as budget and balance sheets, tell the lender about the current financial health of the HOA. Bylaws and CC&Rs tell the lender about the governance structure of the project. Insurance tells the lender how the risk is covered.

The condo questionnaires and meeting minutes show the lender about the day-to-day functioning of the project. They also give a good sense of what the issues are in the project and what projects are upcoming. Together, they give the lender a complete picture of the condo project so that they can decide whether or not to finance it.

Consequences of Non-Compliance

The implications can be wide-reaching and substantial if a condominium development is found to not be eligible. The buyer will be unable to get finance or will have a very difficult time securing it, which means they will need to look elsewhere or walk away. The lack of available finance could result in lower demand, lengthier sales cycles, and a dip in home values.

Existing owners can also run into problems when trying to refinance or sell their apartments. In some cases, the entire building or structure can be found to be non-warrantable, which cuts off access to traditional mortgage products. The consequences of the above results illustrate why it is essential to meet changing lending standards.

Best Practices for Ensuring Condo Financing Readiness

The purpose, in the end, is to prove the condo project is of high quality. To build the operational and financial readiness required for a condominium, you need to put the right proactive measures in place. ‘Fix maintenance issues right away so the small problems don’t become the big ones that might ultimately make you ineligible.

While transparency and organization are also critical. They need to have the financials, insurance, and legal documents ready so lenders can easily access the data they require throughout the evaluation process. Incorporating these practices early on in the project life cycle will help developers sidestep future problems. This way, they can help existing owners and potential buyers.’

Conclusion: Building Confidence Through Preparedness

Condo finance readiness is about more than just the rules—it’s about trust between lenders, borrowers, and other stakeholders. Today’s projects are expected to have reserve studies, structural integrity, and paperwork in order to increase their chances of success.

Condo projects can set themselves up for long-term success and growth by following Freddie Mac condo eligibility standards, FHA condo approval standards, Fannie Mae condo standards, and reserve study requirements, making financing easier and adding value and stability to the community.

Frequently Asked Questions (FAQs)

Why are reserve studies so important for condo financing?

Reserve studies are required for condo financing because they help lenders determine whether an association has adequately funded reserves for maintenance and repairs. A well-funded reserve study is a sign that the association is managing finances prudently and that the property is less likely to require costly special assessments for repairs and replacements in the near future. A well-prepared reserve study also helps lenders evaluate the risk of financing the property. Without a current and fully funded reserve study, the lender may consider the property to be a higher risk and may deny the loan or impose more stringent loan terms.

What structural issues can impact condo loan approval?

Structural problems, such as foundation cracks, water damage, roof damage, or structural corrosion in essential building components, can be a concern when a lender is considering a loan. Lenders will look at inspection reports and engineering findings to ensure the building is safe and to protect the value of the property. Deferred maintenance is also a red flag for lenders because it can indicate that the association is not addressing problems in a timely manner. Even minor issues that go untreated can add up. Properties with known structural problems may have limited financing options or may be required to pay higher interest rates

What documents do buyers typically need from a condo association?

In order to smoothly secure financing and complete due diligence, buyers need to provide a complete set of documents. This includes governing documents (e.g., bylaws and declarations), most recent financial statements, reserve studies, and insurance certificates. Buyers should also provide recent board meeting minutes to highlight any current concerns or upcoming expenses. If available, structural reports also provide reassurance on the condition of the building. By having these documents in order and up-to-date, you will not only be able to facilitate the finance process but also inspire confidence in both lender and buyer. Missing or incomplete documents can delay approval or even stifle your transaction.

How do delinquency rates affect condo financing?

Delinquency rates refer to the percentage of unit owners who are behind on their association fees. High rates of delinquency can be detrimental to condo financing, as they reflect potential financial instability within the association. Lenders may see this as a risk, since unpaid fees can impair the association’s ability to fund repairs or maintain the property. Many lenders have guidelines for acceptable delinquency rates, and exceeding those limits can result in loan denial or more stringent terms. Additionally, high delinquency rates can give buyers apprehension about the future financial health of the condo.

Can a condo still qualify for financing with special assessments?

Yes, a condo can still be financed with a special assessment, but it depends on the situation. Lenders will look at the nature of the assessment, its size, and how often it occurs. If it is a one-time assessment for a necessary improvement, it may not be a deal breaker. However, if an assessment is large or frequent, it could indicate a lack of proper financial planning or reserves, which may be concerning for lenders. As a buyer, it’s essential to understand exactly what you would be responsible for. Clear communication and documentation can help alleviate concerns and increase the chances of financing approval.

NSPIRE

NSPIRE Readiness for Affordable Housing Managers: Building a Pre-Inspection System That Prevents Score Surprises

National Standards for the Physical Inspection of Real Estate (NSPIRE) is one of the biggest changes to affordable housing compliance regulations in the past decade. For the asset managers, property managers, and compliance teams, NSPIRE is not just another inspection program but a novel and much more nuanced way of scoring property conditions.

The previous UPCS and HQS inspection programs, in contrast to the resident-centric NSPIRE approach, tended to focus on identifying observable deficiencies. These programs had a fairly predictable scoring structure and an easier ability to prepare for an inspection in advance. With NSPIRE, the focus shifts toward health, safety, and functional defects. This has presented an opportunity for housing providers to develop new pre-inspection systems to score for and prevent surprises in the inspection results.

The NSPIRE compliance timeline has also been in flux in recent years. Though many programs began compliance with NSPIRE at the same time, each HUD program has moved the date for compliance at least once in the past few years. Currently, Community Planning and Development programs are slated a compliance date of October 1, 2026. 

Voucher-based NSPIRE, or NSPIRE-V, was pushed back to February 1, 2027, to give HUD agencies more time to prepare for the transition. (NAHRO)

In this constantly changing environment, the best housing managers are not simply defensively responding to inspections but proactively developing pre-inspection systems that will prevent score surprises and guarantee compliance.

Understanding NSPIRE: A Shift Toward Health and Safety

NSPIRE embodies a philosophical change in what is considered a quality of housing. Rather than focusing on structural or cosmetic deficiencies, the new standards focus on areas that impact resident health and safety—such as ventilation, electrical hazards, fire safety, and other environmental concerns.

HUD’s “affirmative requirements” is a 100% reflection of this change. These include smoke detectors, carbon monoxide alarms, adequate lighting, and working, safe electrical systems. Although some of these items (such as fire alarms) are not yet scored due to phase-in, they are still cited and must be compliant within required timeframes. (HUD)

Now that the August 2022 category of affirmative requirements will not be scored until October 1, 2026, property managers have had more time to prepare. However, that does not mean that there is a grace period. Properties are still expected to be up to standard, and a deficiency can still trigger corrective action even if it has no effect on scores. 

For managers, that means that readiness is no longer about preparing for an event; it’s about ongoing readiness.

Changing NSPIRE Timeline and What It Means for Managers

One of the biggest challenges of NSPIRE implementation has been the fluid compliance schedule, with HUD extending deadlines multiple times in response to industry concerns, operational challenges, and a need for clearer guidance.

Initially, many programs were expected to achieve compliance by 2023 or 2024. Those deadlines were further extended to 2025, and in some cases, even beyond. Community planning and development programs now have a compliance date of October 1, 2026. The voucher-based NSPIRE system has been extended through February 1, 2027.

These extensions are a necessary reality of the complexity of the transition to NSPIRE, but they also pose a risk to housing providers. Delayed deadlines may make organizations complacent, leaving them with little time to prepare, leading to rushed inspections and incomplete documentation and unexpected scores.

Proactive managers, however, use extensions to their advantage, treating the additional time as a chance to develop robust systems, train staff, and standardize processes. By the time the deadline arrives, they already have a compliant, NSPIRE-ready organization.

Why Score Surprises Happen Under NSPIRE

One of the biggest questions that affordable housing managers have is how unpredictable the scores are in NSPIRE. Properties that have scored well on UPCS or HQS may have unexpected score changes under the new system.

Realizing a “score surprise” often is due to insufficient alignment between what an organization does internally and what NSPIRE requires. Many organizations continue to use legacy checklists or rely on outdated assumptions of what inspectors are looking to see. This can lead to critical deficiencies being missed until the inspection.

Another contributing factor is inconsistent recordkeeping and documentation. NSPIRE relies heavily on documented compliance. Without proper documentation of maintenance, repairs, or inspections, a property may not be able to prove compliance even if it has been addressed.

Staff training is another issue. NSPIRE has new terminology, scoring criteria, and inspection protocols. If maintenance or site staff is not trained, they may not understand what is a deficiency or how to prioritize repairs.

To avoid score surprises, a systematic approach is required to align internal processes with the new NSPIRE expectations.

Building a Pre-Inspection System That Works

A pre-inspection system is the cornerstone of NSPIRE readiness. It converts compliance from ad-hoc and reactive to proactive and continuous.

Essentially, a pre-inspection system is a series of internal inspections that mimic NSPIRE standards conducted at regular intervals, well documented and designed to catch deficiencies before HUD inspectors see them.

The foundation of this process is a standardization of inspection processes, checklists, and documentation across the portfolio. With a high degree of standardization, you minimize variability and maximize accountability.

Technology plays a critical role in pre-inspections, as it enables you to manage, track, assign, and monitor deficiencies while creating a digital audit trail in support of compliance.

Developing an Effective NSPIRE Checklist

An effective NSPIRE checklist is a tool that reflects the priorities and purposes of the NSPIRE framework, not just a simple list of items to be inspected.

It must cover all of the key inspection areas, from units and common areas to building systems, and include the criteria required by HUD guidance. 

While there should be room for customization, the core checklist should be standardized across the portfolio.

It is also critical that the checklist be updated as HUD releases new guidance or adjusts requirements.

NSPIRE Scoring: Understanding How Properties Are Evaluated

NSPIRE scoring is severity-based. Scoring methods used in the past often focused on quantity of deficiencies, whereas NSPIRE focuses more on deficiencies that have potentially serious health and safety consequences.

In the NSPIRE system, more serious deficiencies will result in greater deductions to the property’s score. Therefore, a few serious deficiencies can negatively impact the score more than many less serious defects.

The delayed scoring of some affirmative requirements until 2026 has, in the short-term, lessened the negative impact of some deficiencies on overall scores. Nevertheless, those items are still cited and must be corrected within a certain period of time. (NAHRO)

Managers must understand the scoring methodology to allocate resources wisely and prioritize repairs. Paying attention to the high-impact deficiencies will allow organizations to achieve a higher score and maintain the safety of residents.

HCV NSPIRE Administrative Procedures and Operational Impact

The adoption of NSPIRE for Housing Choice Voucher programs adds another layer of administrative work. HUD has published detailed guidance on procedures for inspections, compliance, and reporting under NSPIRE.

These procedures are required by all public housing agencies that administer voucher programs and are establishing a common set of standards for inspections. The compliance deadline for these programs has been extended several times and is currently scheduled for February 1, 2027. (HUD)

What does this mean for them? They must assess voucher units using NSPIRE standards, even if full compliance will not be due for some time. There is a transition period to make the changes, train staff, and update policies.

The change from HQS to NSPIRE also involves changes in documentation and reporting. Agencies need to make sure they can capture and store the information required in the new system.

Recordkeeping and Documentation: The Backbone of Compliance

Good recordkeeping is a cornerstone of NSPIRE readiness. It is the documentation required to prove compliance and provide support for decision-making throughout the organization.

This includes inspection reports, maintenance records, work orders, and corrective actions. Records should be accurate, complete, and readily available.

Digital systems are especially useful for documentation. They enable an organization to centralize information, monitor progress, and create reports. This boosts efficiency but also transparency and accountability.

Good recordkeeping also involves consistency. All staff should use the same processes to record information so that the data is comparable across properties.

Training and Culture: Creating a Compliance-Driven Organization

No pre-inspection system is useful without trained staff. Training should include all aspects of NSPIRE, from inspection standards and scoring rubrics to documentation guidelines.

Culture is also important. Organizations need to develop a culture of compliance, one that sees inspections as a critical part of operations, that holds people accountable, and that rewards all staff for maintaining property standards.

Leaders play a key role in developing a culture of compliance. By making compliance a high priority and giving staff the resources they need, leaders can help achieve NSPIRE readiness.

Conclusion: From Reactive Inspections to Proactive Readiness

NSPIRE has fundamentally changed the way that we conduct inspections in affordable housing. The challenge for managers is not just to be prepared for NSPIRE but to do so in a predictable, consistent way.

The only way to achieve that goal is to build a pre-inspection system. Aligning internal standards with NSPIRE standards, keeping our documentation up to date, and investing in staff training will eliminate surprises at score time and ensure compliance.

The extended timelines for NSPIRE give us an advantage in our preparation, but they should not be used as a justification to delay action. They give us a unique opportunity to build systems that will sustain NSPIRE readiness.

NSPIRE readiness is about more than passing inspections. It’s about creating safe, high-quality housing for our residents and establishing the highest standard of excellence we can.

Frequently Asked Questions (FAQs)

What is NSPIRE, and why is it important for affordable housing managers?

NSPIRE (National Standards for the Physical Inspection of Real Estate) is a HUD inspection model designed to assess the safety, functionality, and habitability of affordable housing units. It replaces older inspection systems with a stronger focus on resident health and safety. For housing managers, NSPIRE is critical because inspection scores directly impact funding, compliance status, and reputation. A poor score can lead to corrective actions or financial risk. Understanding NSPIRE standards helps managers proactively maintain properties, prioritize repairs, and ensure units meet required conditions before official inspections occur.

What is a pre-inspection system, and how does it help?

A pre-inspection system is an internal process used to evaluate property conditions before an official NSPIRE inspection. It involves routine checks, standardized inspection checklists, and staff training to identify and fix issues early. This system helps managers catch deficiencies such as safety hazards, maintenance gaps, or compliance issues in advance. By addressing problems proactively, housing teams can avoid last-minute surprises and improve overall inspection outcomes. A well-structured pre-inspection system also promotes accountability, ensures consistency across units, and builds confidence in maintaining inspection readiness year-round.

What are the key components of an effective NSPIRE readiness plan?

An effective readiness plan includes regular unit inspections, clear documentation processes, and defined maintenance workflows. Staff should be trained on NSPIRE standards and understand how to identify deficiencies. A tracking system for repairs and follow-ups is essential to ensure no issue is overlooked. Communication with residents also plays a role, encouraging them to report concerns promptly. Scheduling periodic mock inspections helps simulate real conditions and prepare teams. Combining these elements creates a structured approach that reduces risk and ensures properties consistently meet inspection requirements.

How often should pre-inspections be conducted?

Pre-inspections should be conducted regularly, not just before official inspections. Many organizations adopt quarterly or biannual inspection cycles to maintain consistent property standards. High-risk units or properties with past deficiencies may require more frequent checks. Additionally, spot inspections can help ensure ongoing compliance. Regular inspections allow managers to identify patterns, address recurring issues, and prevent small problems from becoming major violations. Maintaining a consistent schedule ensures that properties remain inspection-ready at all times, rather than relying on last-minute fixes before NSPIRE evaluations.

How can managers prevent score surprises during NSPIRE inspections?

Preventing score surprises requires proactive planning and strong internal systems. Managers should implement routine inspections, maintain detailed records, and ensure timely completion of repairs. Using standardized checklists aligned with NSPIRE criteria helps identify issues early. Training staff and clearly assigning responsibilities improves accountability. Leveraging technology for tracking and reporting can streamline the process. Engaging residents in reporting maintenance concerns also adds an extra layer of oversight. By staying organized and consistent, managers can reduce uncertainty, improve inspection outcomes, and maintain high-quality housing standards.

HOA collections

HOA Collections and Delinquency: A Due-Process Workflow for Notices, Payment Plans, Liens, and Vendor Oversight

Collections in HOAs—Are They Legally Sound?

Homeowners’ Associations (HOAs) are vital to the success of residential communities by ensuring that the community is well-financed. When homeowners cease to meet these obligations, then the HOA has to put in place a collections process that is not only consistent with contract enforcement and statutory requirements but also consumer protection laws. Collections in HOAs are not a simple administrative undertaking and are legally sensitive.

A properly designed collections workflow must protect homeowners’ due-process rights while also protecting the community, including its owners, against any financial risk. This may include an understanding of the factors, such as a delinquency policy, proper notice, and attorneys. 

Federal law, including Regulation F under the Fair Debt Collection Practices Act (FDCPA) and Florida Statute §720.3085. It is just a few of the legal guidelines that should be understood by HOA board members, property managers, and individuals advising them. 

What HOAs can do to collect money is outlined in a mix of legal documents, state laws, and federal rules. The association’s declaration, bylaws, and rules outline the contract that all homeowners have signed to pay and allow the HOA to charge a fee, collect the money, and take action against anyone who doesn’t pay. 

State law further supports this contractual right, providing associations with additional power. Specifically, §720.3085 says associations have a “lien on each parcel for any unpaid assessments, authorized by a declaration of covenants, bylaws, or other governing documents” (Florida Senate). This statutory lien secures not only the unpaid assessments but also any interest, late fees, and reasonable costs for collection. 

HOA Delinquency

Understanding HOA Delinquency

Delinquency Policy and Procedure

Delinquency is when a homeowner fails to pay their assessment by the due date stated in the governing documents. This might start as an honest mistake, but if not corrected promptly, it can quickly become a legal situation.

Delinquency has effects beyond the individual homeowner. Associations depend on assessment income to pay their obligations. Unpaid dues can take away from the budget, which results in deferred maintenance, higher fees for other homeowners, and/or the need for special assessments.

Finally, from a governance perspective, it is important to enforce delinquency policies consistently. Selective enforcement of delinquency can not only lead to legal action but also erode trust within the community. A delinquency policy that has clear guidelines and is applied strictly will help avoid problem situations.

The Due-Process Workflow for HOA Collections

Collections workflow is designed to allow homeowners multiple chances to cure delinquency prior to the use of higher-level enforcement actions. The workflow reflects legal requirements and best practices to ensure fairness in collection actions by the HOA.

The collections workflow starts with normal billing but escalates to delinquency when payment is missed. At the initial stage of delinquency, typical notices may be courtesy notices/reminders, which do not necessarily make the situation urgent.

At later stages of delinquency, the association is required to send statutory notices to the homeowner. In Florida, for example, the association is not allowed to file a lien without first sending a written demand with at least 45 days for the homeowner to correct the delinquency.

Notice Requirements and Compliance

Notice requirements are a crucial part of due process in HOA collections. They keep homeowners aware of their duties and the consequences of turning down a dues-paying house. Additionally, notice requirements keep a record of what was said to homeowners in support of enforcement actions.

Florida law requires a notice of intent to record a lien to be sent before a lien is filed. The notice must give 45 days of payment and itemize the amounts due. The lien will be void if that notice is not given, and the association will not be able to recover attorney fees.

Notice must also be given in an enforceable manner. Most commonly, this means certified mail. This is a key to maintaining accurate recordkeeping on the part of homeowners and associations.

Regulation F adds notice requirements at the federal level for third-party collectors. These include a validation notice, explaining costs, and the consumer’s rights.

Regulation F and the Validation Notice

Regulation F is an important step forward in debt collection. Collectors must now send debt validation notices that disclose all the details of the debt—the amount, the identity of the creditor, and an itemized breakdown of charges. 

The notice also triggers a 30-day “debtor dispute” period, during which collection efforts must be paused if the consumer wants to dispute the debt. This requirement allows consumers to have their debts fully verified before creditors can take enforcement action. 

Our community has discussed the practical implications of these rules, and one user explained that Regulation F requires collectors to send a “validation notice that gives the consumer significantly more information” and “options to dispute the debt.”

The HOA Lien Process Under Florida Statute §720.3085

The lien process is an integral part of HOA collections. Under Florida law, the association’s lien is an effective tool that holds the unpaid assessments and costs.

A credible claim of lien must identify the property, the owner’s name, the association’s name, and the amount owing. The lien covers the current debts as well as future assessments that accrue before the claim is resolved. 

Once documented, the lien is in the public record and can hinder the owner from selling or refinancing the association’s property. It is also the basis of further enforcement procedures, including foreclosure.

Florida law also allows for the contesting of liens. The homeowner may file a notice of contest, in which case the association must bring a suit within a period of time. This keeps the lien active and prevents a lien from remaining unchallenged for years.

Payment Plans and Loss Mitigation

Payment plans are a common tool for avoiding litigation and resolving delinquency. They enable homeowners to pay off balances, easing financial hardship and giving the association a better chance of recovery.

A well-structured payment plan should be in writing and establish payment amounts, due dates, and the penalties for default. It should also establish whether interest and fees will continue to accrue during the repayment period.

The importance of clarity is illustrated in this anecdote: “I was misinformed by a conflict of interest and was given a payment plan that was never documented, which meant they kept collecting on my account and added fees.”

Offering payment plans can also help the association’s legal position by establishing good faith and reasonableness. Courts are more likely to be favorable to enforcement actions when the association has attempted to accommodate the homeowner.

Vendor Oversight and Third-Party Collections

HOA collections

Many HOAs will use outside vendors to manage delinquent accounts. These may be property managers, collecting agencies, and law firms. While this could be more efficient, it adds risk.

The association is ultimately responsible for ensuring that all collection activities are in compliance with applicable law and governing documents. That means being able to actively monitor vendor performance and having clear expectations set out in the contract.

Missteps in vendor-managed collections often involve improper fees, lack of communication, and failure to comply with notice requirements. These are common themes in community discussions of this issue, and governance is a key consideration.

A collection policy is extremely important. It ensures fair treatment. This is to advocate for having a clear policy that guides vendor action and increases consistency.

Financial Implications of HOA Collections

Delinquency can have major financial consequences for the association and its members. Unpaid assessments can result in budget shortfalls, requiring the association to defer maintenance or increase fees levied on other homeowners.

Collection costs can also be high. 

Attorney fees, administrative costs, and other collection-related expenses can add up. Although these costs can potentially be recovered under state law, they can still divert cash flow from the association.

For homeowners, the financial impact can add up rapidly. Interest, late fees, and collection costs can increase the amount owed dramatically. Sometimes, these costs accumulate to the point where the homeowner is risking foreclosure.

Best Practices for HOA Collections

The foundation of a successful HOA collections program is clarity, consistency, and compliance. Associations should create and implement delinquency policies that clearly define each step of the process, from initial notice through enforcement.

Recordkeeping matters. Consistent and detailed documentation of notices, payments, and communication provides a platform for enforcement and helps to avoid disputes.

Communication is key. Engaging homeowners early often helps avoid escalation. Providing payment plans and openness helps to maintain relationships and improve results.

Technology can help too. Billing, tracking, and communication technology help to streamline the process and reduce room for error.

Conclusion

Collections, liens, and enforcement are legal processes that require strict compliance and due process. Enforce collection and preserve the association’s finances. Establish clear policies and enforce them. Maintain accurate records to protect the association and its leaders. Oversee the vendors to ensure compliance. 

Florida Statute §720.3085 requires collections to have a due-process workflow from notice sent to enforcement of liens. Reg F requires additional transparency for the consumer. Collecting, filing a lien, and enforcement are more than just collecting but require due process and transparency.

FAQs 

1. What is the proper first step in handling HOA delinquency?


The first step is early identification and clear communication. As soon as a homeowner misses a payment, the HOA should send a polite reminder notice outlining the balance due, due date, and any applicable late fees. This initial step should focus on resolution, not enforcement. Providing clear account statements and easy payment options helps prevent escalation. Documentation is essential—every notice, email, and interaction should be recorded. Acting early reduces the likelihood of long-term delinquency and sets a professional tone for the collection process.

2. How should an HOA structure its notice and escalation process?


An HOA should follow a structured, step-by-step notice process. This typically begins with a friendly reminder, followed by a formal late notice, and then a demand letter if the balance remains unpaid. Each notice should clearly state the amount owed, deadlines, and consequences of non-payment. Timelines between notices must comply with governing documents and local laws. Consistency is critical to ensure fairness across homeowners. A well-documented escalation process protects the HOA legally and ensures homeowners are given an adequate opportunity to resolve their balances.

3. What makes an effective HOA payment plan?


An effective payment plan is realistic, clearly documented, and mutually agreed upon. It should outline the total balance, installment amounts, due dates, and any conditions for remaining in good standing. Flexibility can help homeowners catch up while maintaining a steady cash flow for the HOA. The agreement should also include consequences for missed payments, such as plan termination or escalation. Keeping communication open throughout the plan encourages compliance. Proper documentation ensures transparency and helps avoid disputes while providing a structured path to resolving delinquent accounts.

4. When and how should an HOA proceed with liens?


Liens should be considered only after multiple notices and reasonable attempts to resolve the delinquency have failed. Before filing a lien, the HOA must ensure compliance with state laws and governing documents, including providing proper notice to the homeowner. The lien secures the unpaid balance against the property, protecting the HOA’s financial interest. Documentation is critical, including payment history and all communication records. Filing too early can create conflict, while delaying too long may risk recovery. A balanced, compliant approach ensures fairness and legal protection.

5. How can HOAs effectively manage collection vendors and attorneys?


Managing vendors and attorneys requires clear expectations and regular oversight. The HOA should define the scope of work, fee structures, and reporting requirements upfront. Regular updates on account status, legal actions, and costs help maintain transparency. Boards should review vendor performance and ensure compliance with laws and community policies. Communication between the HOA and vendors must be consistent to avoid errors or delays. Proper documentation and accountability ensure that collection efforts remain professional, cost-effective, and aligned with the HOA’s goals and homeowner relationships.

Rental Registration

Rental Registration, Housing Registries, and Licensing Inspections: Building a City-by-City Compliance Calendar

Property managers today require rental registration for their properties as a result of changes in urban development laws. Housing registries, rental licensing inspections, and periodic reporting of rental operations are all established under local government law in major metropolitan areas throughout the United States.

Inability to meet due dates or to comprehend particular requirements will create financial penalties, increase your risk of litigation, and restrict your ability to run your rental business. Property managers must now develop and operate their companies with strong compliance systems to comply with these new regulations. This requires implementing effective tracking systems for monitoring and maintaining their legal obligations.

Although there are many differences regarding registration duties for rental properties in different U.S. cities, they all have many similarities in terms of requirements that must be met at specific times. Therefore, the most efficient manner to manage rental registration duties in multiple cities is to develop a compliance calendar for each city.

A compliance calendar will ensure all deadlines are met, schedules are organized for inspections, and documentation remains current. The guidebook provides steps for developing a complete rental registration process between cities, listing primary requirements for each city, explaining procedures for conducting business, and providing guidelines for maintaining compliance.

Understanding Rental Registration and Why It Matters for Compliance

Rental registration is the process by which a property owner registers their residential rental property with the appropriate local agency. This registration ensures that the property complies with all of the necessary safety, legal, and operational requirements. It also establishes a system where municipalities can monitor their available rental properties, as well as enforce any rental rules and regulations effectively.

Property managers have to complete the task that include multiple renewals, inspections, and reporting requirements. If a property manager fails to comply with any of the above-mentioned requirements, they face financial or legal consequences.

Further, there are often specific types of information that must be provided by a property manager during registration. Recognizing the magnitude of the rental registration process helps property managers place a priority on their compliance initiatives. It also emphasizes the importance of having structured systems. Without this, the compliance process is more difficult, especially as the number of residential rental opportunities increases within the property manager’s portfolio.

Key Differences in Rental Property Registration Across Major Cities

Different cities handle rental registration by using different enforcement methods based on how property managers operate in their respective jurisdictions. For instance, the New York City rental property registration requires property owners to file an annual report and tenant occupancy information.

Washington DC’s regulatory scheme requires that rental property management obtain a basic business license before renting out any units, and a thorough inspection before leasing it. In comparison, the registration process in New York City has a different set of rules than the Washington DC system. 

These rent-stabilization deadlines create additional challenges for property managers, as they must meet all deadlines associated with the annual registration deadlines. The fact that each city has its own unique characteristics. Using only one method of compliance would likely result in missing critical pieces of information.

Rental Property Registration NYC Requirements and Annual Obligations

The most comprehensive rental property registration program in the US exists in New York City. All residential buildings in New York are registered with the appropriate housing authority on an annual basis. This process allows the housing authority to maintain up-to-date information regarding the property owner and its management. 

In addition to providing all of the property management information, the registration process requires information about their property ownership, construction details, the number of tenants, and their company.

Every organization is required to submit any operational changes to the housing authorities by a certain date if the organization wants to remain in compliance. Failure to submit all operational changes results in both financial penalties and regulatory enforcement issues for the organization.

Organizations are responsible for monitoring multiple deadlines. Therefore, making sure that all documentation is submitted on time in order to ensure that the organization operates as efficiently as possible.

Housing Registry Landlord Responsibilities and Data Accuracy Requirements

Housing registry landlord obligations extend beyond initial registration. Property managers must maintain accurate, up-to-date information in municipal registries. This includes ownership details, contact information, and unit occupancy status.

Accuracy is critical as municipalities rely on registry data for enforcement and communication. Incorrect or outdated information can lead to missed notices, compliance violations, or inspection delays. Property managers must implement processes to regularly verify and update data.

Additionally, some cities require periodic confirmations or renewals of registry information. These updates may coincide with rental registration deadlines independently. Tracking these requirements manually becomes complex without a structured system.

From an operational perspective, maintaining registry accuracy requires coordination across teams. Leasing, maintenance, and administrative staff must communicate changes effectively. Prioritizing data accuracy, property managers can reduce compliance risks and improve operational efficiency.

Basic Business License Rental Property Inspection DC Explained

In Washington, DC, rental registration is closely tied to licensing requirements. Property managers must obtain a basic business license and a rental property inspection in DC before legally leasing residential units. This process ensures that properties meet safety and habitability standards.

The inspection process involves reviewing building conditions, safety systems, and compliance with housing codes. Properties must pass inspection before a license is issued. Any deficiencies must be corrected promptly to avoid delays.

Additionally, licenses must be renewed periodically, requiring ongoing compliance with inspection standards. This creates a recurring operational requirement that property managers must track carefully.

Unlike NYC’s registration-focused system, DC emphasizes licensing and inspections as core components of Rental Registration. This difference highlights the need for city-specific compliance strategies.

Integrating inspection schedules and license renewals into a compliance calendar ensures that deadlines are met. It also helps property managers avoid interruptions in leasing operations.

Rent Stabilized Registration Deadline and Its Operational Impact

The rent stabilized registration deadline is a critical component of Rental Registration in regulated markets. Property managers must file annual registrations for rent-stabilized units, including rent amounts and tenant information. These filings ensure compliance with rent control regulations. New York City’s HPD Annual Property Registration is a city registration for certain residential buildings, with an annual deadline of September 1. New York State’s HCR rent registration is a separate process for rent-stabilized apartments, with an annual deadline of July 31.

Missing deadlines can result in significant penalties and restrictions on rent increases. This directly impacts revenue and operational planning. Therefore, tracking these deadlines is essential for maintaining financial stability.

Additionally, rent-stabilized properties often require detailed documentation and record-keeping. Property managers must ensure that all data is accurate and submitted on time. This adds complexity to compliance workflows.

From an operational perspective, integrating the rent-stabilized registration deadline tracking into a compliance calendar is essential. Automated reminders and centralized tracking systems can help prevent missed deadlines.

By effectively managing these requirements, property managers can maintain compliance and protect revenue streams.

Building a City-by-City Compliance Calendar for Rental Registration

Creating a city-by-city compliance calendar is the most effective way to manage Rental Registration obligations. This calendar centralizes all deadlines, inspections, and reporting requirements across jurisdictions.

A well-structured compliance calendar should include:

  • Annual Rental Registration deadlines for each city
  • Inspection schedules and licensing renewal dates
  • Rent stabilized registration deadline tracking, where applicable.
  • Housing registry landlord update requirements
  • Documentation submission timelines and renewal cycles

Each entry should include detailed instructions and responsible parties. This ensures accountability and reduces the risk of missed deadlines. Property managers should also include buffer periods to allow for unexpected delays.

Additionally, digital tools can enhance calendar management. Automated reminders and task tracking systems improve efficiency and accuracy. These tools are especially valuable for multi-city portfolios.

By implementing a centralized compliance calendar, property managers can streamline operations and maintain consistent compliance.

Integrating Compliance Workflows Into Property Management Operations

A compliance calendar is only effective when integrated into daily operations. Property managers must align Rental Registration workflows with existing processes to ensure consistency and accountability.

This integration involves assigning responsibilities to specific team members. Each compliance task should have a designated owner accountable for its completion. Clear role definition reduces confusion and improves execution.

Additionally, workflows should include verification steps to ensure accuracy. For example, registry updates should be reviewed before submission. This reduces the risk of errors and compliance violations.

Technology can play a key role in workflow integration. Property management systems can automate task assignments and track progress. This improves visibility and ensures that deadlines are met.

By embedding compliance workflows into operations, property managers can create a proactive approach to Rental Registration management.

Leveraging Technology for Multi-City Rental Registration Tracking

Technology is essential for managing Rental Registration across multiple jurisdictions. Manual tracking methods are prone to errors and inefficiencies, especially for large portfolios.

Modern property management platforms offer features such as automated reminders, document storage, and compliance tracking. These tools centralize information and improve accessibility for teams.

Key technological capabilities include:

  • Automated deadline tracking for Rental Registration and inspections
  • Centralized document management for licenses and registrations
  • Integration with leasing and maintenance systems
  • Real-time reporting and compliance dashboards

These tools enable property managers to monitor compliance status across all properties. They also reduce administrative workload and improve accuracy. Additionally, cloud-based systems ensure that information is accessible from anywhere.

This is particularly important for teams managing properties in multiple cities. By leveraging technology, property managers can streamline Rental Registration processes and improve operational efficiency.

Common Compliance Risks and How to Avoid Registration Violations

There are many potential risks related to rental registration compliance that might occur if there are no systems in place to mitigate them. By understanding what the risk factors are, property managers can put into place measures to prevent these types of issues from occurring.

Some of the common risk areas that exist when it comes to rental registration compliance include:

  • Tracking registration or renewal deadlines improperly.
  • Inaccurate or outdated data for property owners renting units.
  • Missing the timeframes for scheduling necessary inspections.
  • Failing deadlines for completing registrations for renting units for local rent stabilization.
  • Misunderstanding the city’s specific regulations related to rentals based on where the rental property is located.

To mitigate the risks of rental registration compliance issues, property management should develop proactive plans and then audit them on a regular basis. Property managers should also train their personnel concerning the process for renting properties in order to reduce non-compliance. 

In this way, property managers will reduce their exposure to violations and minimize the penalties associated with failure to comply with rental registration compliance requirements.

Creating Standard Operating Procedures for Registration and Inspections

There is no particular order to follow the standard operating procedures while managing rental registration and inspections. Therefore, consistently documenting these processes will help reduce the dependency on people’s experience.

An effective SOP will typically contain:

  • Step-by-step instructions for completing Rental Registration-related tasks.
  • A description of the documentation that needs to be provided, along with submission methods and procedures.
  • The process of preparing for and conducting inspections, as well as following up after an inspection is completed.
  • The roles and responsibilities of the various parties involved in performing compliance-related tasks.

The SOPs should be documented thoroughly and made available to all relevant staff members. Any updates made to maintain compliance with changing regulations should happen regularly so that the SOPs remain compliant.

The training program should reinforce the procedures in the SOPs to ensure they are being carried out consistently. This is especially critical for new employees.

Implementing SOPs allows property managers to have a consistent approach to compliance issues and become more efficient in operating their businesses.

Scaling Compliance Strategies Across Growing Property Portfolios

The registration process for rental properties becomes increasingly challenging as property owners expand their rental property holdings. A system has been developed to monitor the rapid growth of rental registration requirements and regulatory changes that exist for businesses. 

The property management compliance strategy requires centralization to support its development efforts. The organization achieves better compliance monitoring as it utilizes a single system to handle its entire portfolio requirements, decreasing duplicate work efforts. 

The agencies achieve uniform implementation of their property policies through the establishment of standardized operating procedures. The entire portfolio uses primary operating procedures and compliance calendars that implement city-specific regulations without any exemptions. 

The staffing model for property management operations adjusts according to the number of units managed. Property management maintains control over its rental registration operations through the successful execution of its scaling strategies.

Conclusion

Property management companies must carry out rental registration procedures which they need to fulfill their primary obligation to remain compliant with regulations. Property managers must conduct their operations according to the various rules that each city establishes for its jurisdiction. Property managers need to develop specific systems that enable them to fulfill the operational requirements established by different cities.

The process involves updating landlord details and conducting initial business license inspections for rental properties. Establishing a compliance calendar system in a structured method helps manage duty-to-comply requirements. The calendar system enables organizations to track their compliance deadlines together with inspections while making sure they keep accurate records.

Property managers use simple tools to establish ongoing compliance across their entire property portfolio. The guide explains the rental registration process, which organizations need to complete for their regulatory compliance requirements. with precision and confidence.

FAQs

1. How do property management companies register their rental properties?

Registration with local authorities is a method to ensure that the property has all ordinances and codes associated with it, rather than being listed. The registration also provides a basis for maintenance, safety, legal, and operational issues of the property to be compliant with regulations.

2. How does the NYC registration process differ from other cities for rental properties?

The NYC registration requires the landlord to submit yearly reports to the NYC Department of Housing regarding the condition of their tenants’ rental property. Many other areas use state law to ensure compliance when renting to their tenants, such as requiring inspections and licenses for rental properties.

3. What does a landlord need to do to add their property information to the housing registry?

Each landlord must provide their actual property information to the local authority and the ownership documents to the housing registry database maintained by the local authority. All landlords should ensure that their contact and tenancy documents are current, accurate, and regularly maintained.

4. What does the basic business license include when rental property inspections are done?

The property inspection reviews each building to determine whether the property complies with available safety and health standards. Factors inspected include the current property condition, compliance with all applicable governing ordinances & any building permits obtained by the landlord.

5. Why is it important to track the rent stabilization registration deadline?

Tracking the rent stabilization registration deadline gives the company a way for us to guarantee that we comply with all rent control laws. If the owner fails to timely submit the rent stabilization registration in two consecutive years, then there are penalties associated with rent control restrictions.